

In this quick-dive, I’m looking at MDB 0.00%↑. Currently, it is down around 17-18% as of this writing for one core reason. The current CEO has stepped down to go to META 0.00%↑. CJ Desai spent less than a year as CEO with Dev Ittycheria now filling in as interim president and CEO once more.
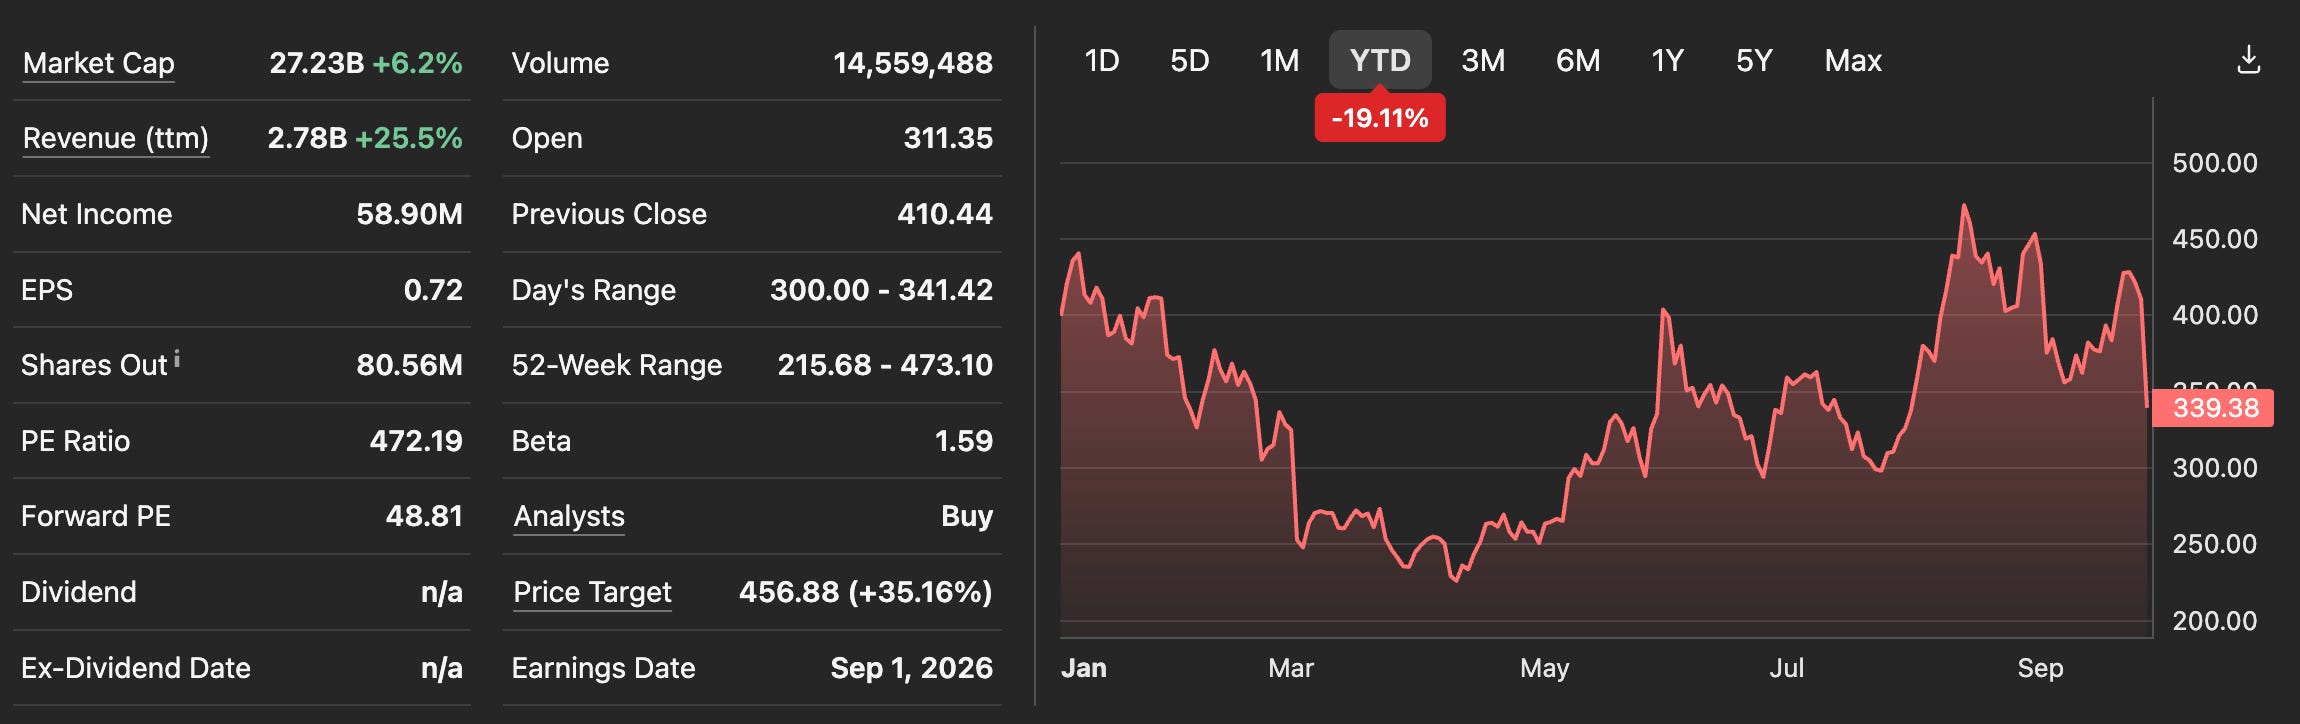
Looking at the overview of MDB 0.00%↑, you can see that the stock is down roughly 20% for the year as they struggle with high SG&A and R&D costs bogging down their gross profits. This is resulting in a very thin net income at the end of the day.
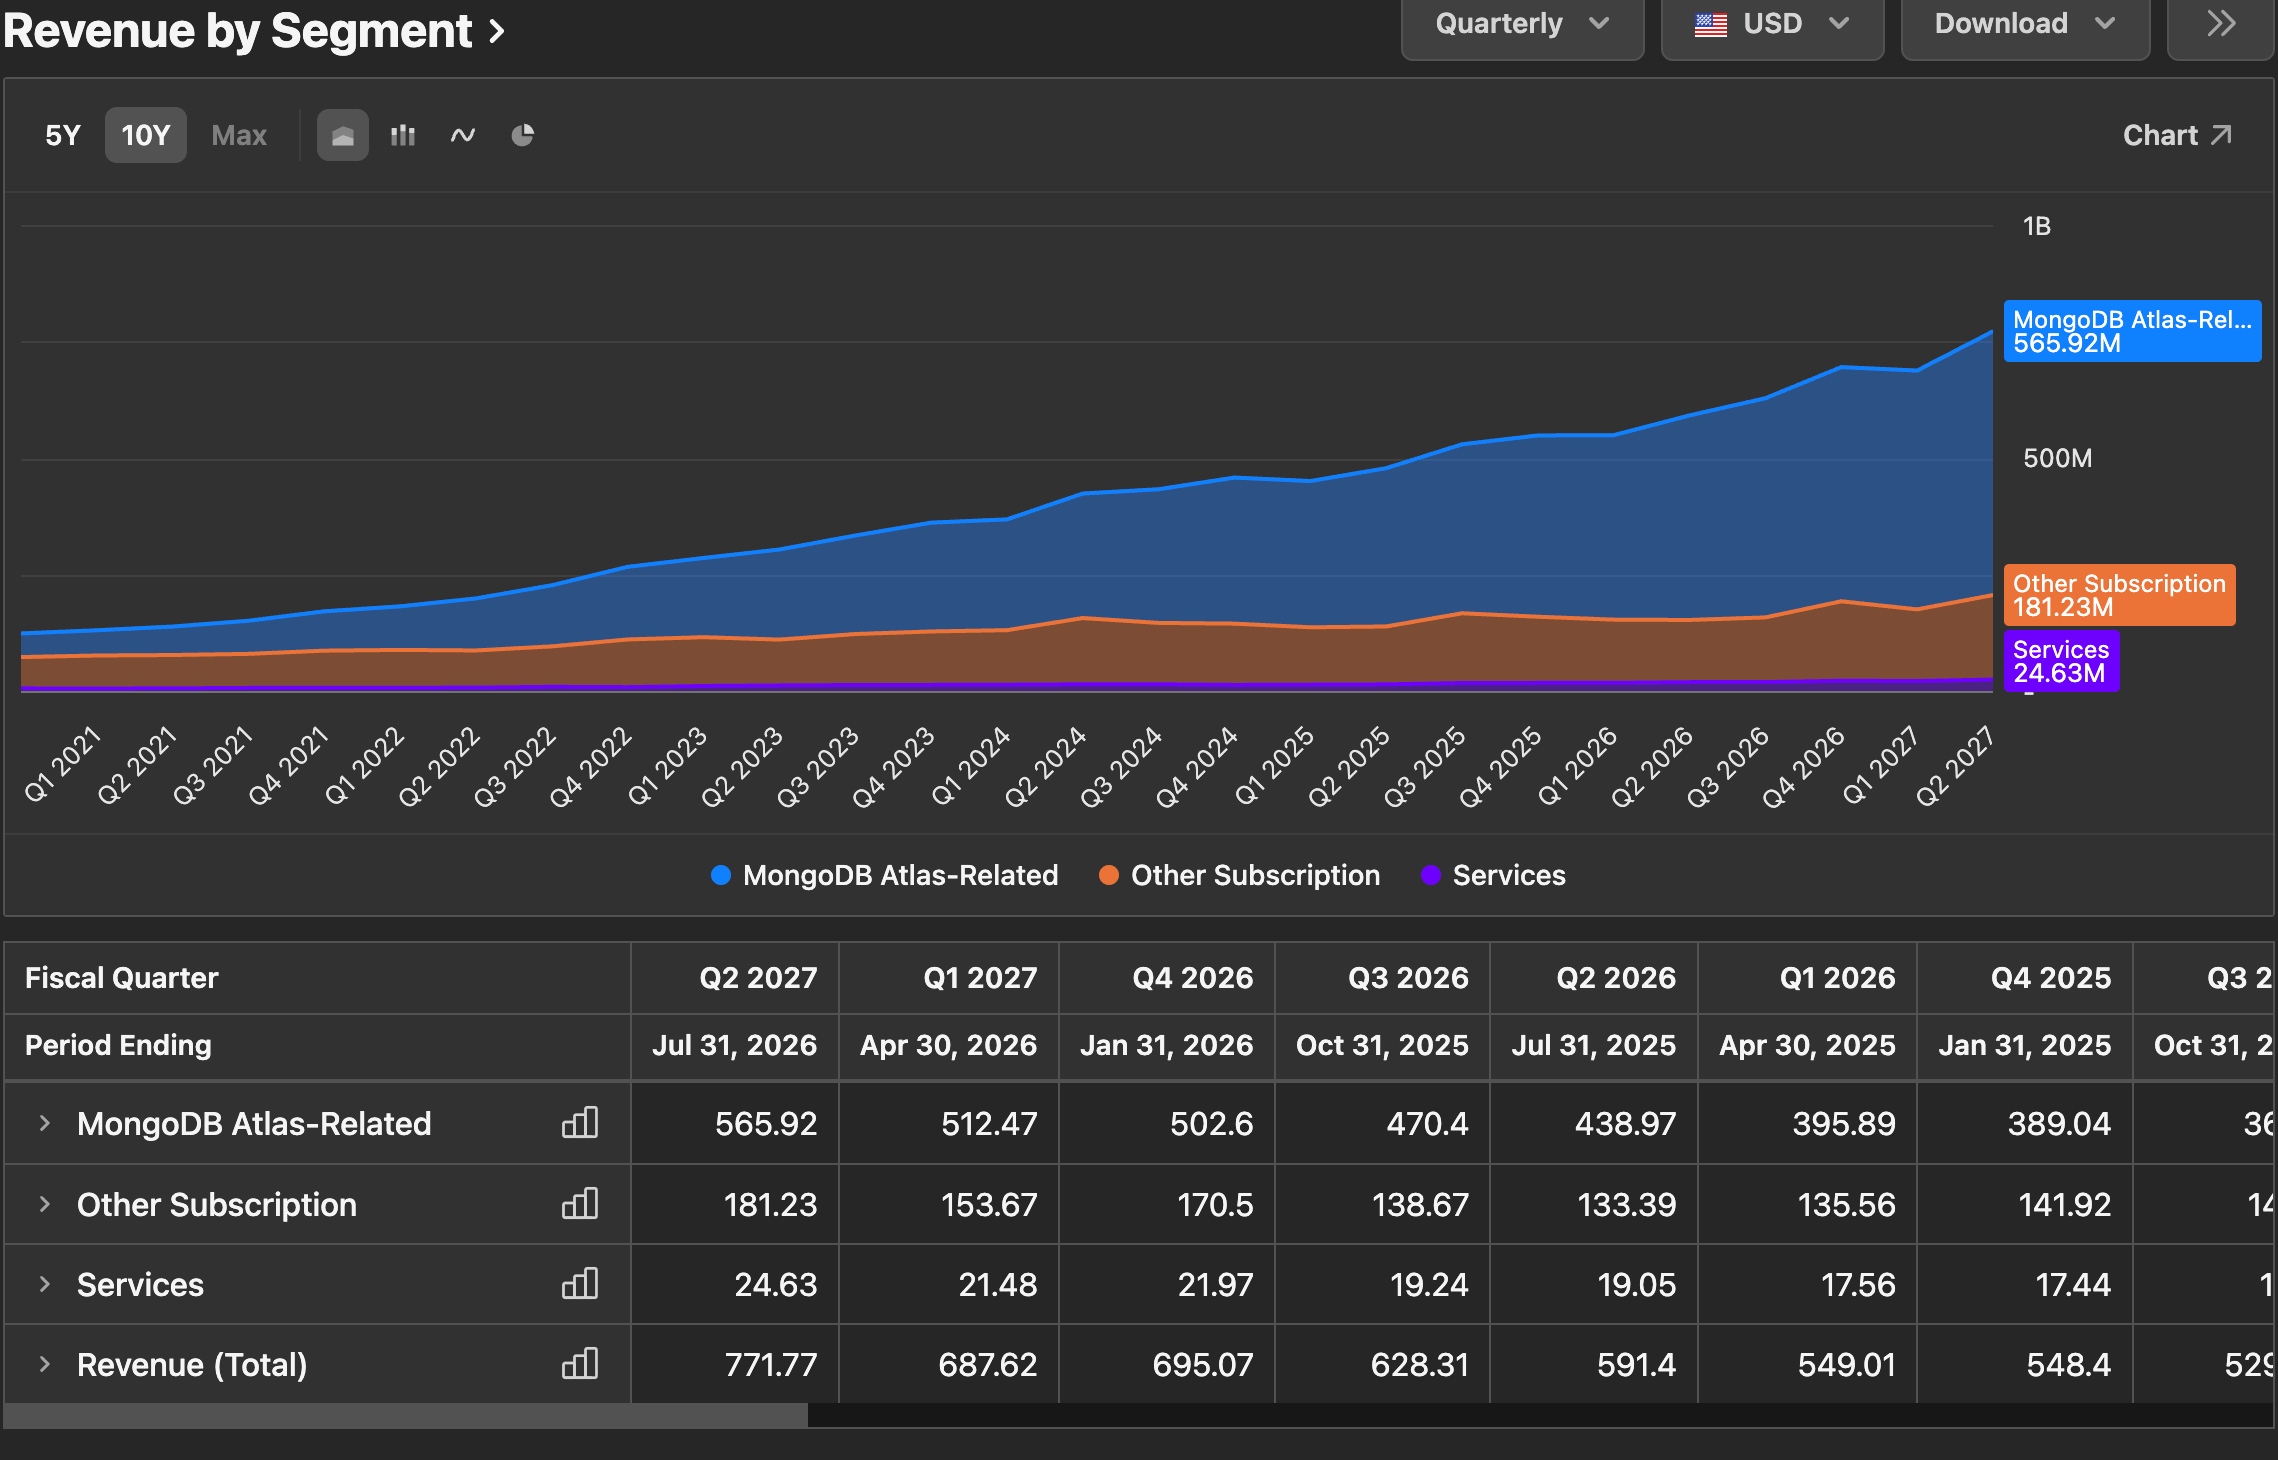
They report revenue in 3 segments: MongoDB Atlas-Related (fully managed, cloud-based database-as-a-service (DBaaS)), other subscription (on-premise database offerings), and services (consulting and training). The DaaS segment is by far the largest revenue generating segment as MDB 0.00%↑ positions it as an intelligent data layer for modern generative AI and machine learning workloads.
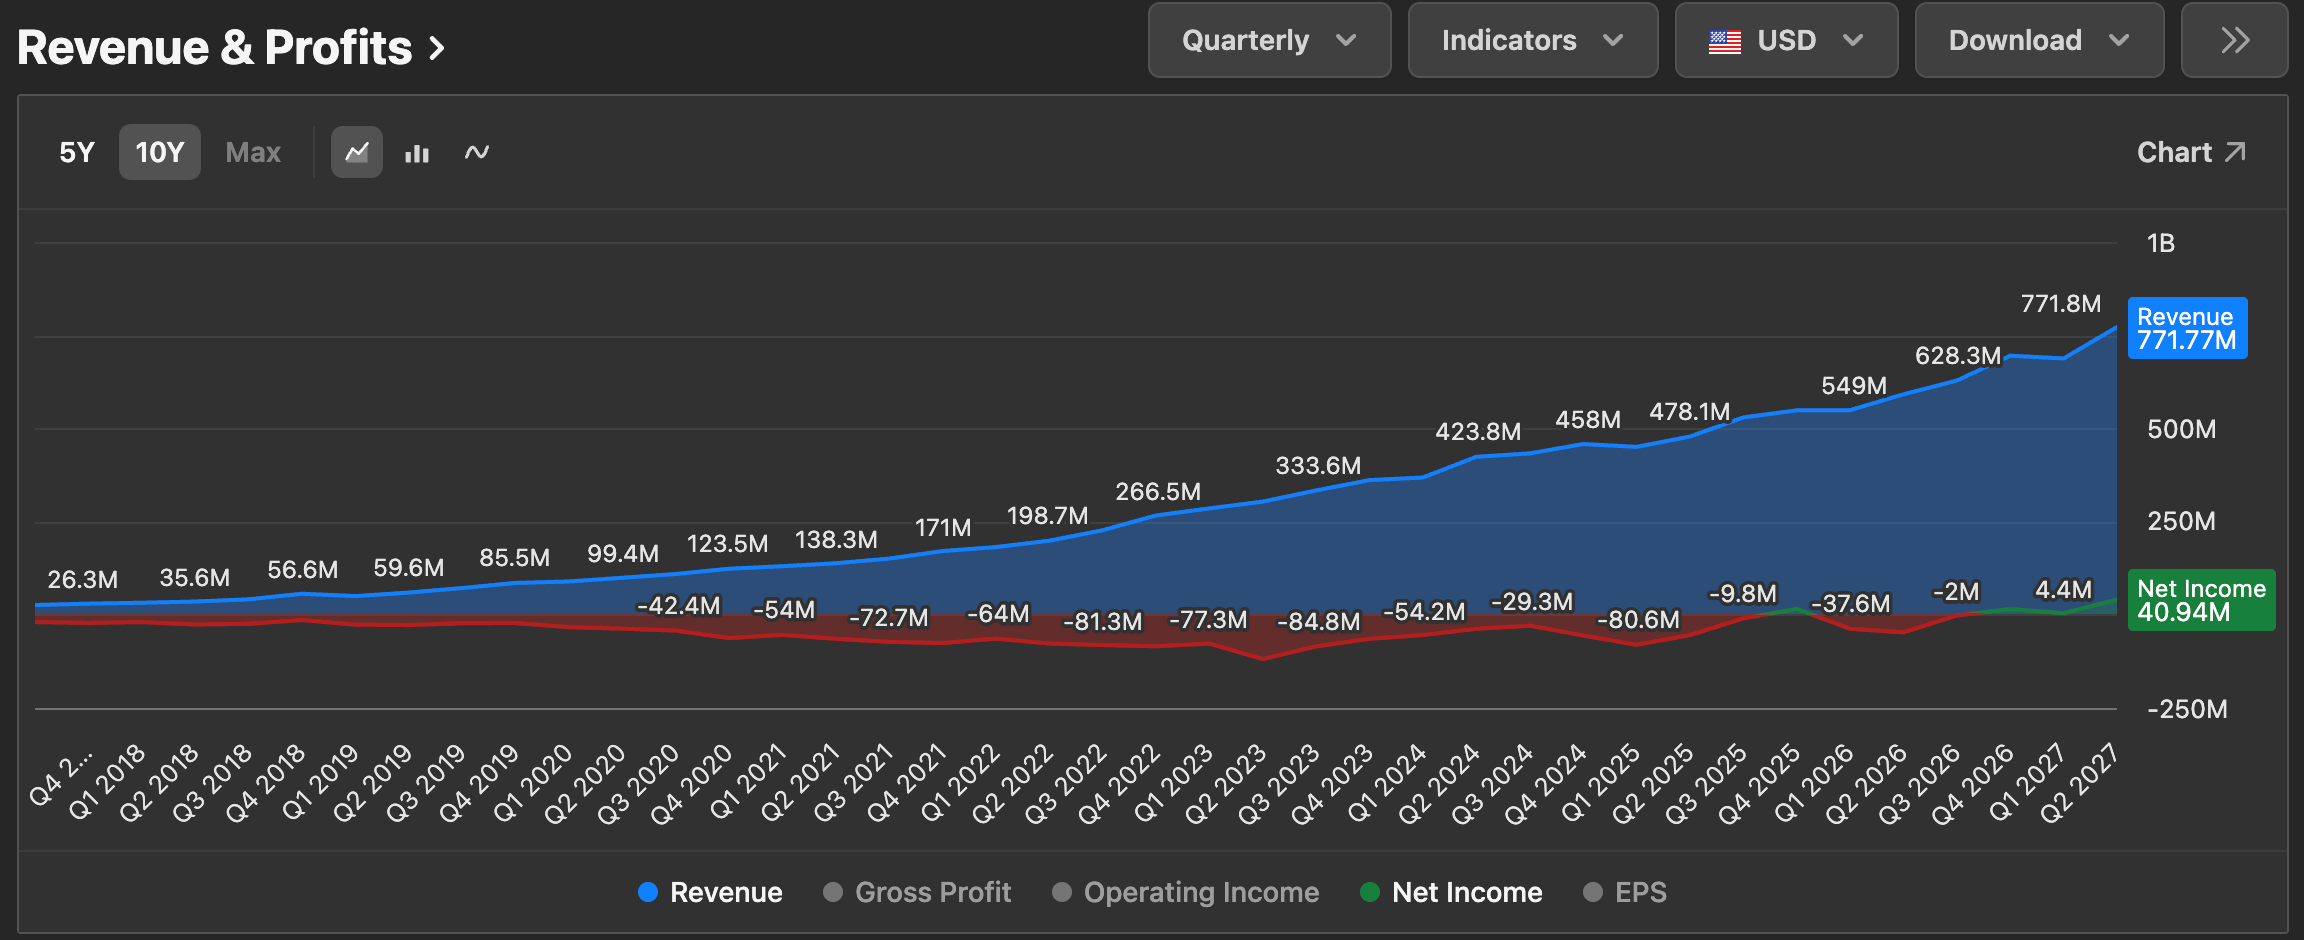
The business has only just begun getting positive net income in the last quarter, but you can see just how much the cost of sales and operating expenses are taking out of the revenues in this chart above.
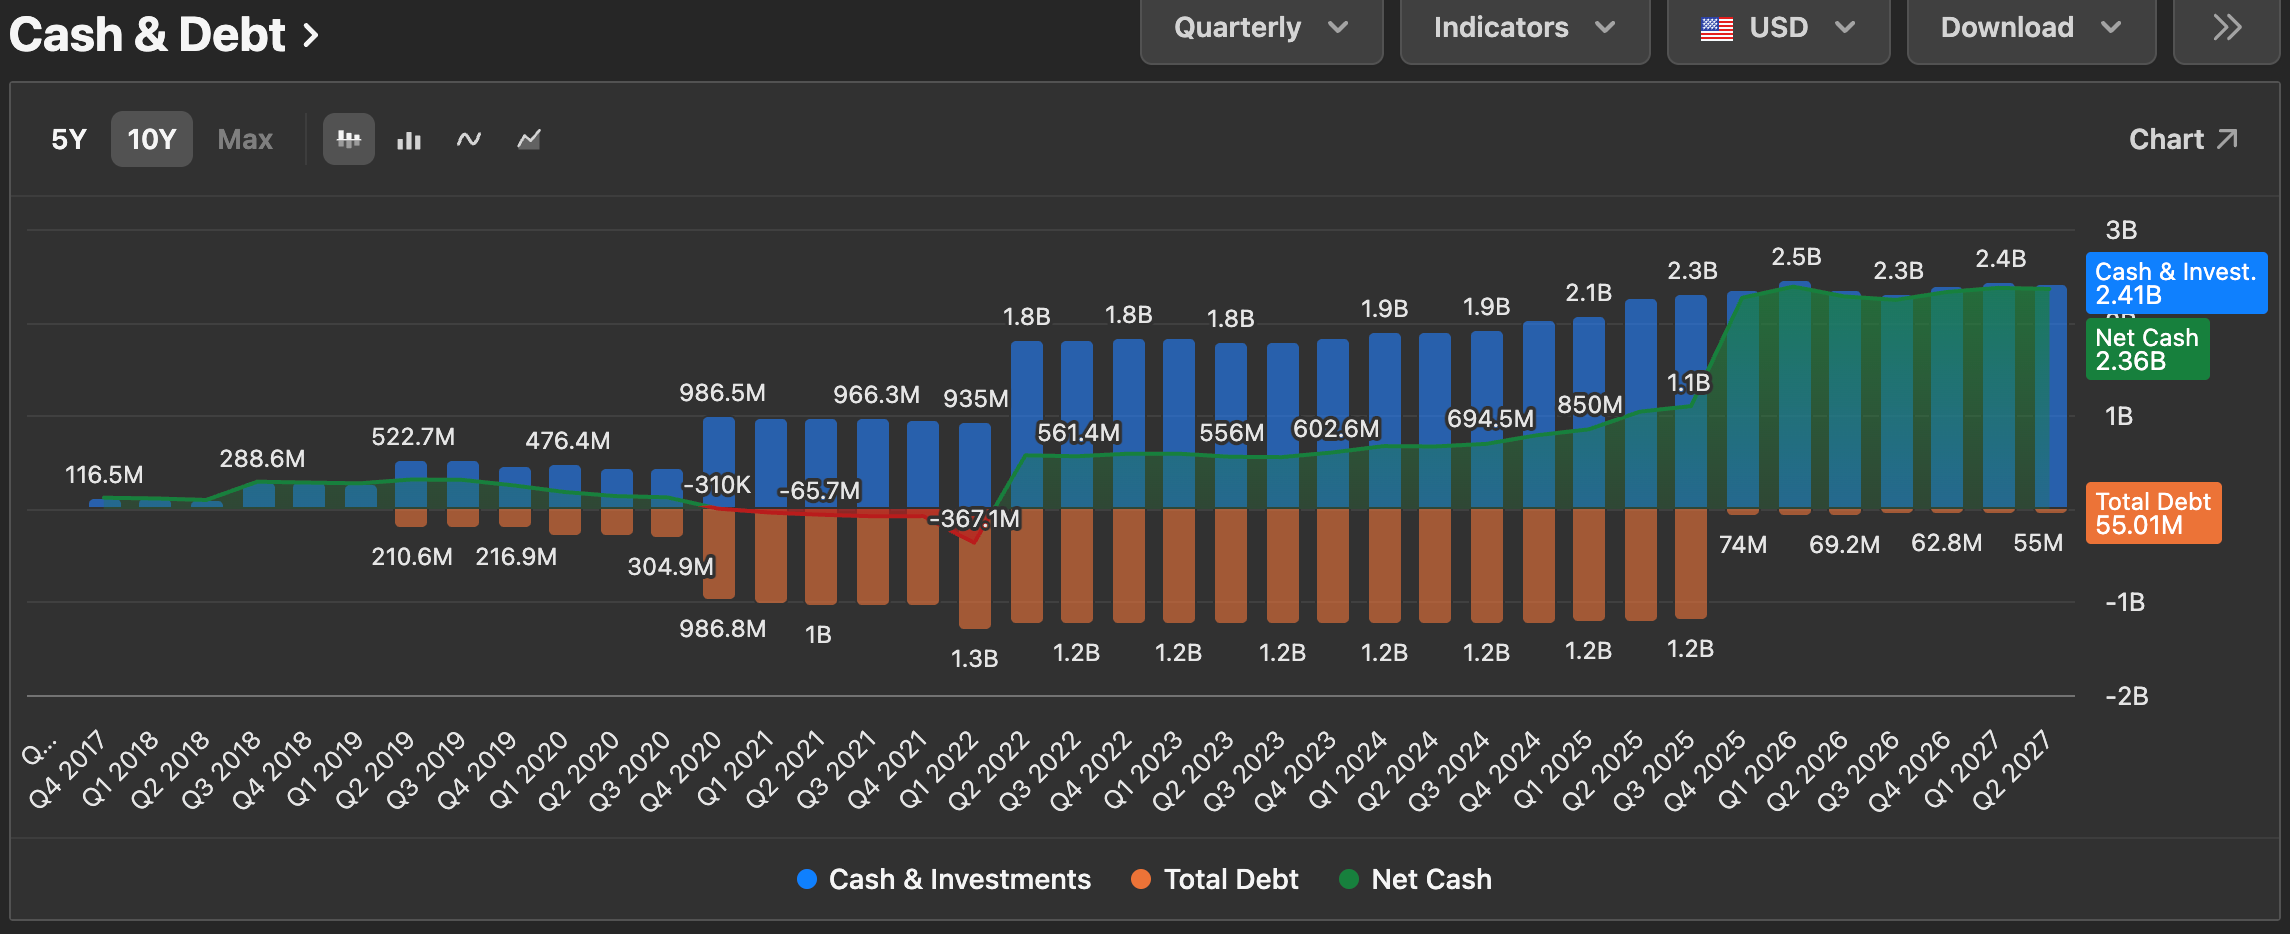
One positive note is their use of leverage. They have about $2.36B in net cash with $2.41B in cash & investments and only $55.01M in total debt. With this strong balance sheet, they are able to operate with high SG&A and R&D for a time to build the business.
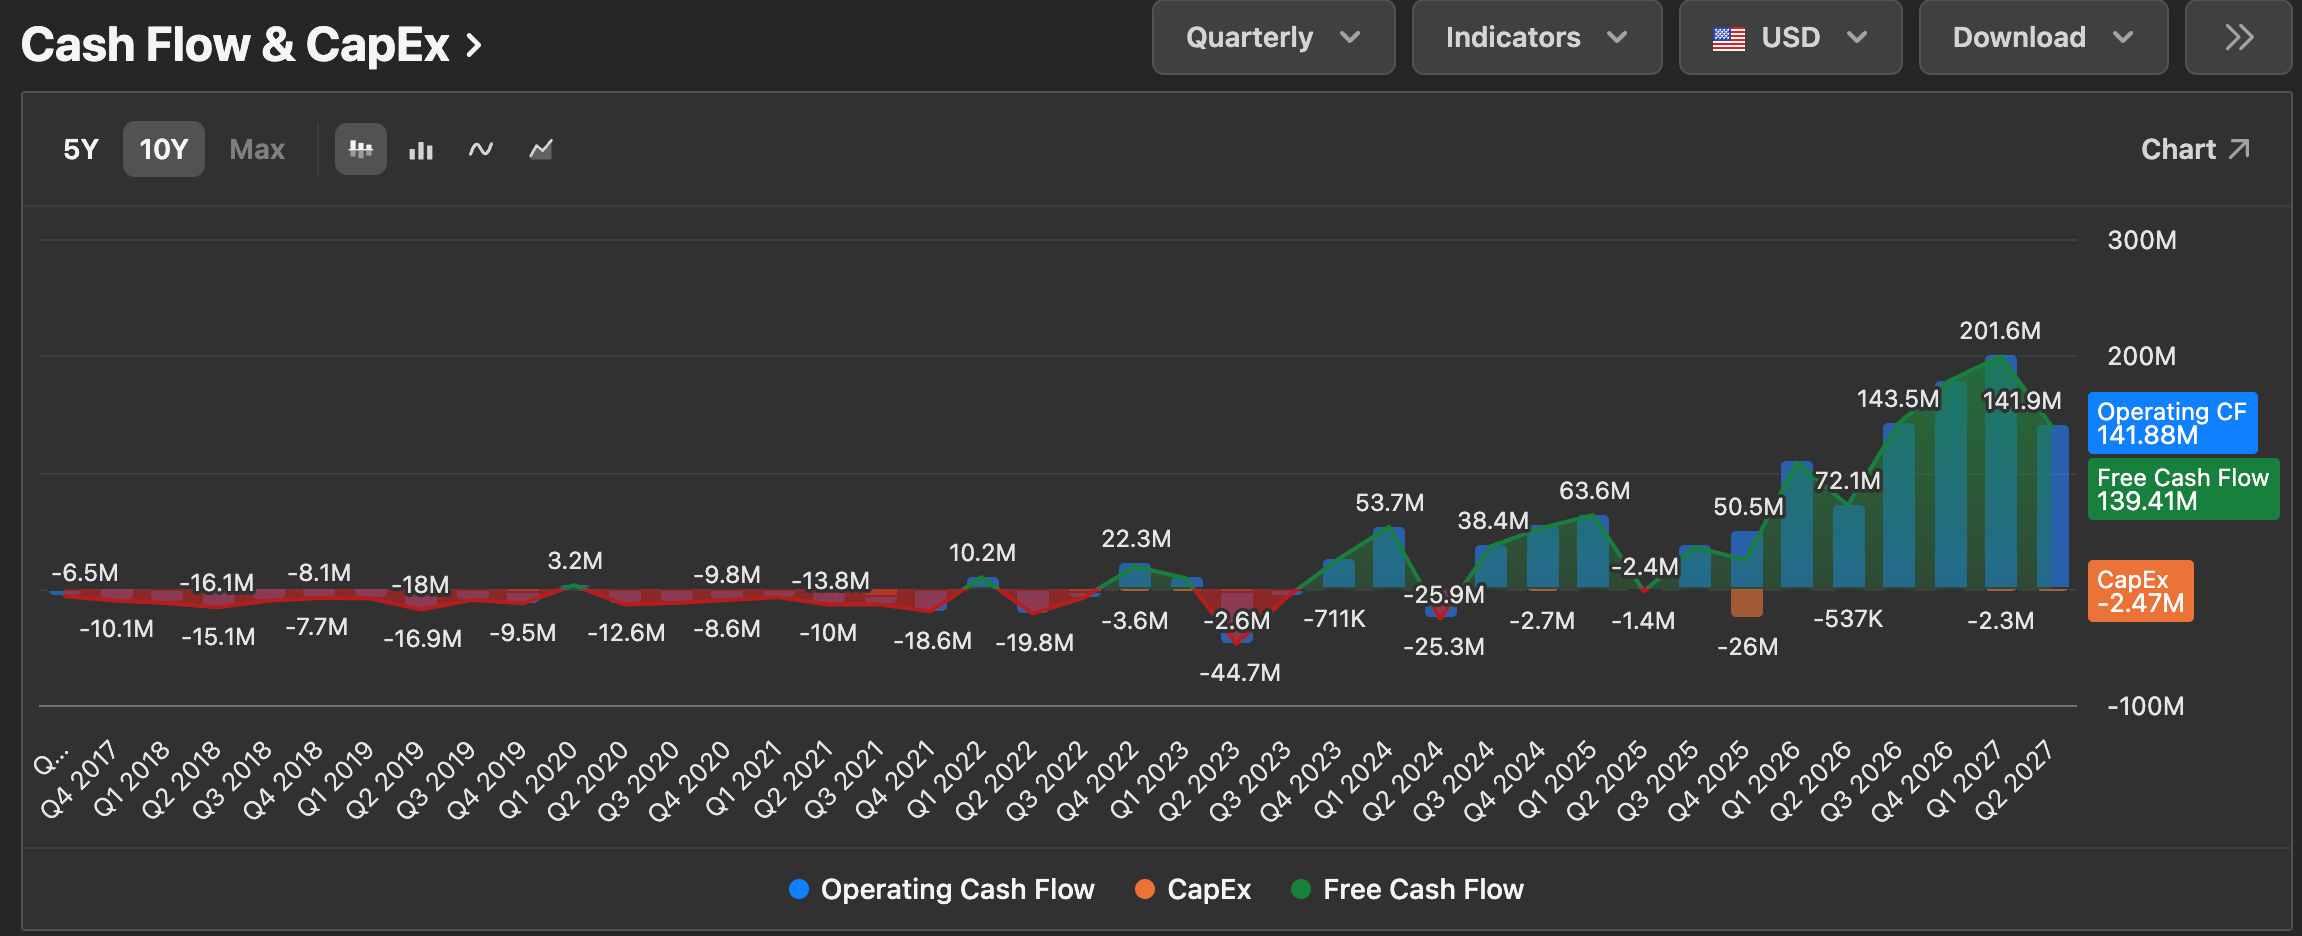
In addition, their free cash flow growth is strong because their capital expenditures are very small. They reported only -$2.47M of capex last quarter with $141.88M of operating cash flow resulting in $139.41M of free cash flow.
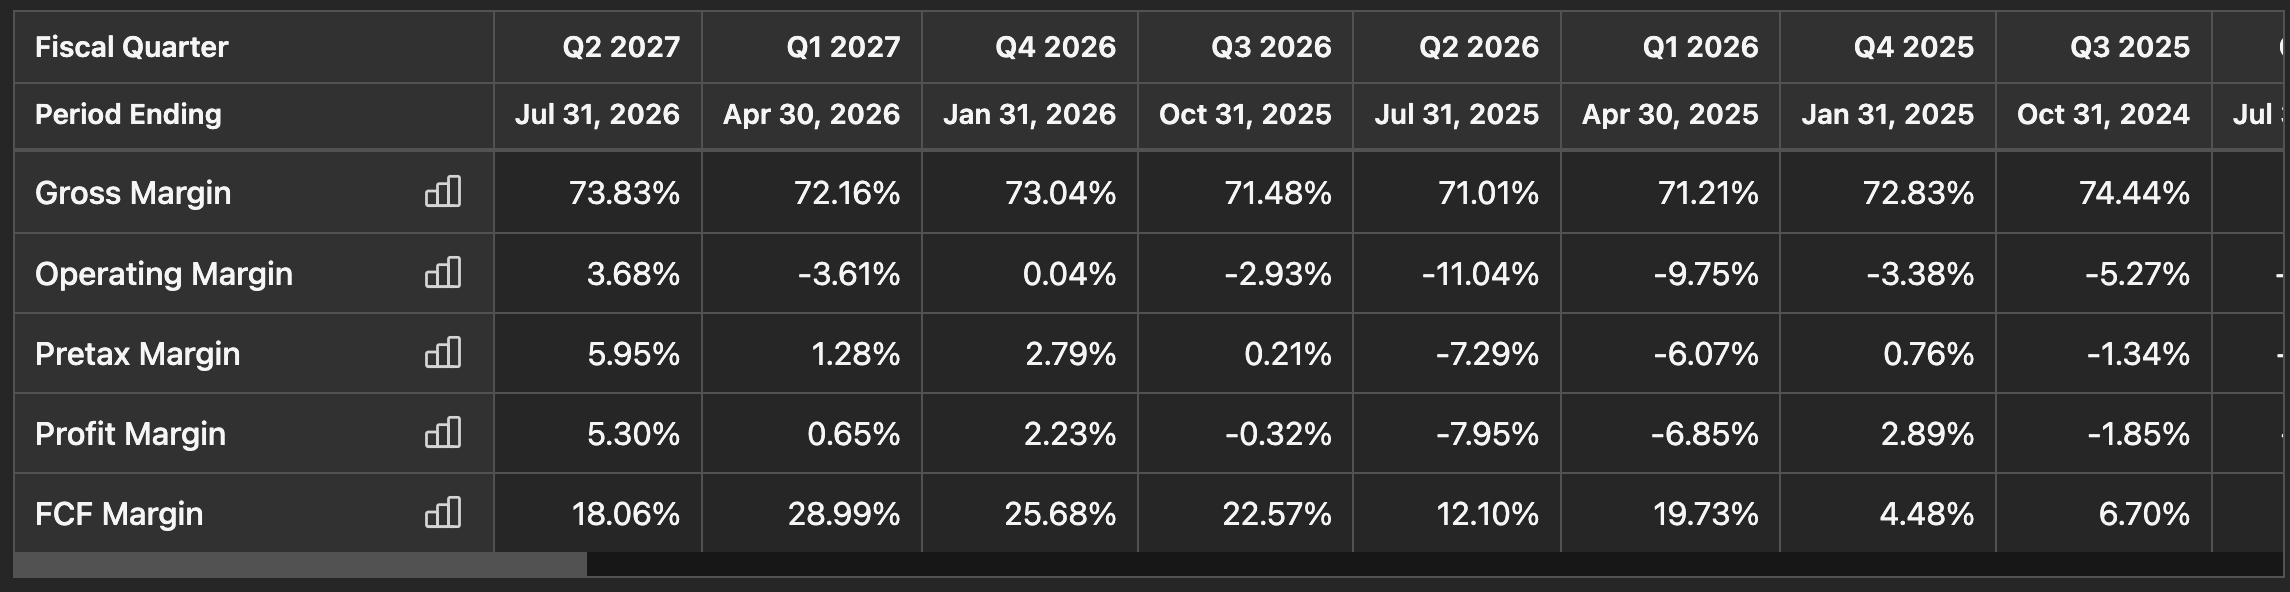
Gross margins are good but operating margins are slim with 3.68% posted for last quarter and a profit margin at 5.3%. FCF margins are at 18.06% which is good but definitely down from previous quarters.
Analysts are still positive on the stock with a $456.88 stock price which is 35.16% higher than the current price. The PE ratio and forward PE ratio are not that valuable as they are straddling unprofitability.
As a value investor, I will be steering clear of this even with the drop for now. If the business continues to improve net profit margins and increasing FCF margins while tackling their high operating expenses, I might take another look.
As always, my content is not financial advice. Please do your own due diligence when investing your own money.