

To start off, I bought ~$2500 of GPIQ 0.00%↑ in the portfolio with the option premiums I received from writing options on CASY 0.00%↑ and AMR 0.00%↑.
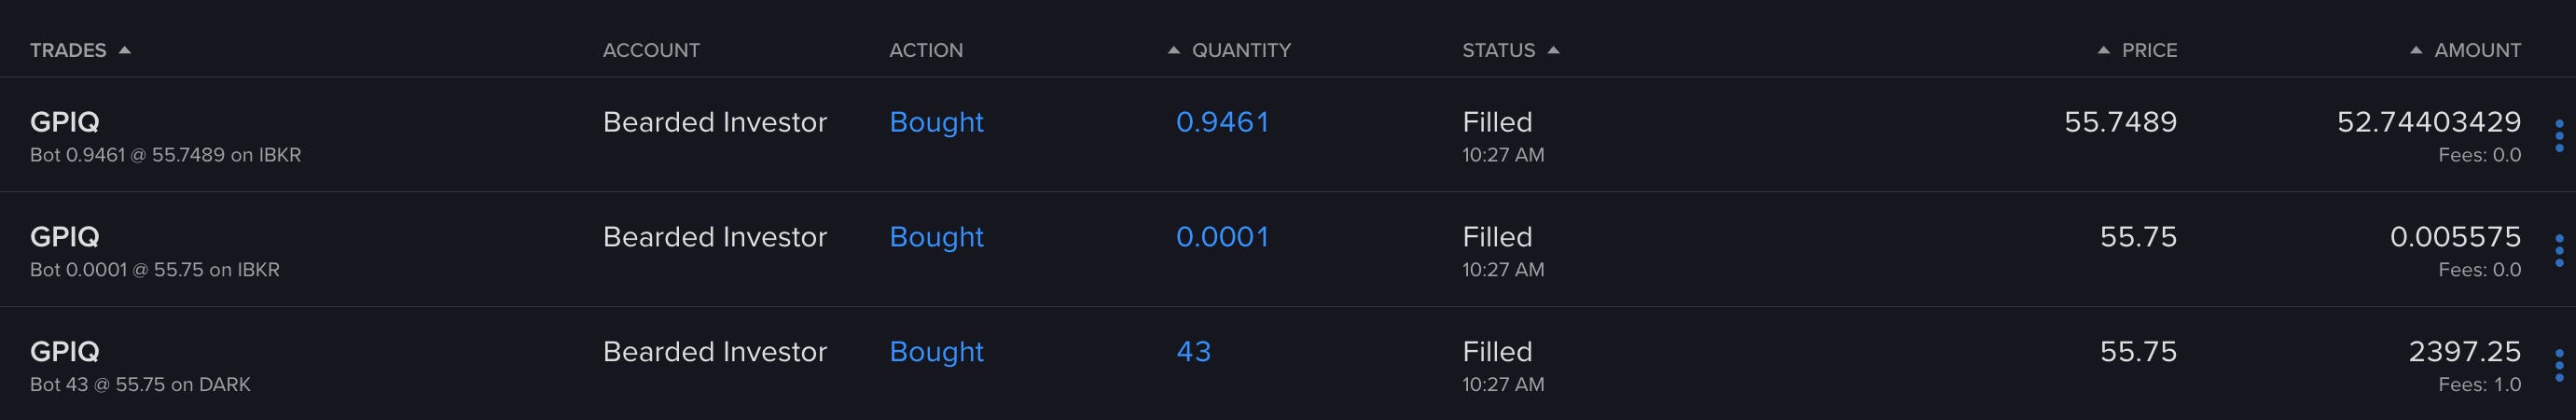
This brings me up to ~230 shares in GPIQ 0.00%↑ so far. Now let’s discuss the elephant in the room. The US met coal equities are taking a beating and they account for big paper losses in my account today. The account is down $4k-$5k on those equities alone, which in all honesty, doesn’t bother me because those are long-term bets.
However, on the positive side, selling the AMR 0.00%↑ covered call proved to be correct and I’m currently up over 50% on that option.
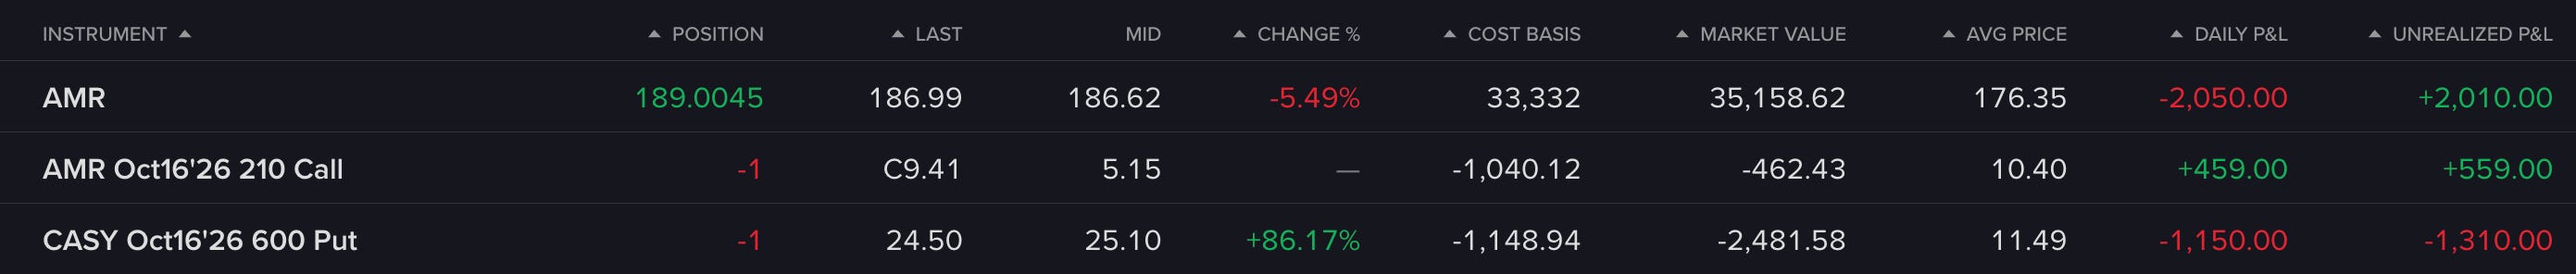
The CASY 0.00%↑ option is not doing well and has dropped below the $600 strike of the contract as of the time of this writing.
My plan accounted for this possibility when I sold the put. I will hold the option instead of rolling for now. If I’m assigned from now till expiration in mid-October, then I will sell covered calls on the resulting 100 shares of CASY 0.00%↑ to offset margin interest.
The stock has already removed the excess froth and extreme valuation from this huge price drop. P/E has dropped to roughly 28 from 40+. Analysts are positive on the stock with a ~$800 average price target. With a strong balance sheet, management guidance for store growth, M&A possibilities, geographic white-space growth, and so many other factors, I’m not concerned about holding these shares AFTER such a large price drop.
I’m attaching their investor day and other presentation here for you to make your conclusions, but in my opinion, this drop was a strong overreaction:
https://investor.caseys.com/static-files/282c53ca-5901-433f-bda2-730dc4bd84b9
https://investor.caseys.com/static-files/adcff974-e24d-4004-82be-a68b9b66c273
I will have a deep-dive on CASY 0.00%↑ after my BABA 0.00%↑ deep-dive so stay tuned for that.
As always, my content is not financial advice so please do your own due diligence before investing your money.