

MU 0.00%↑ reported stellar numbers. There is no other way to spin it. Looking at their full FY 26 through all quarters, you can see the crazy growth they posted. In the latest quarter, they had 379.27% revenue growth and 1060.47% EPS growth.
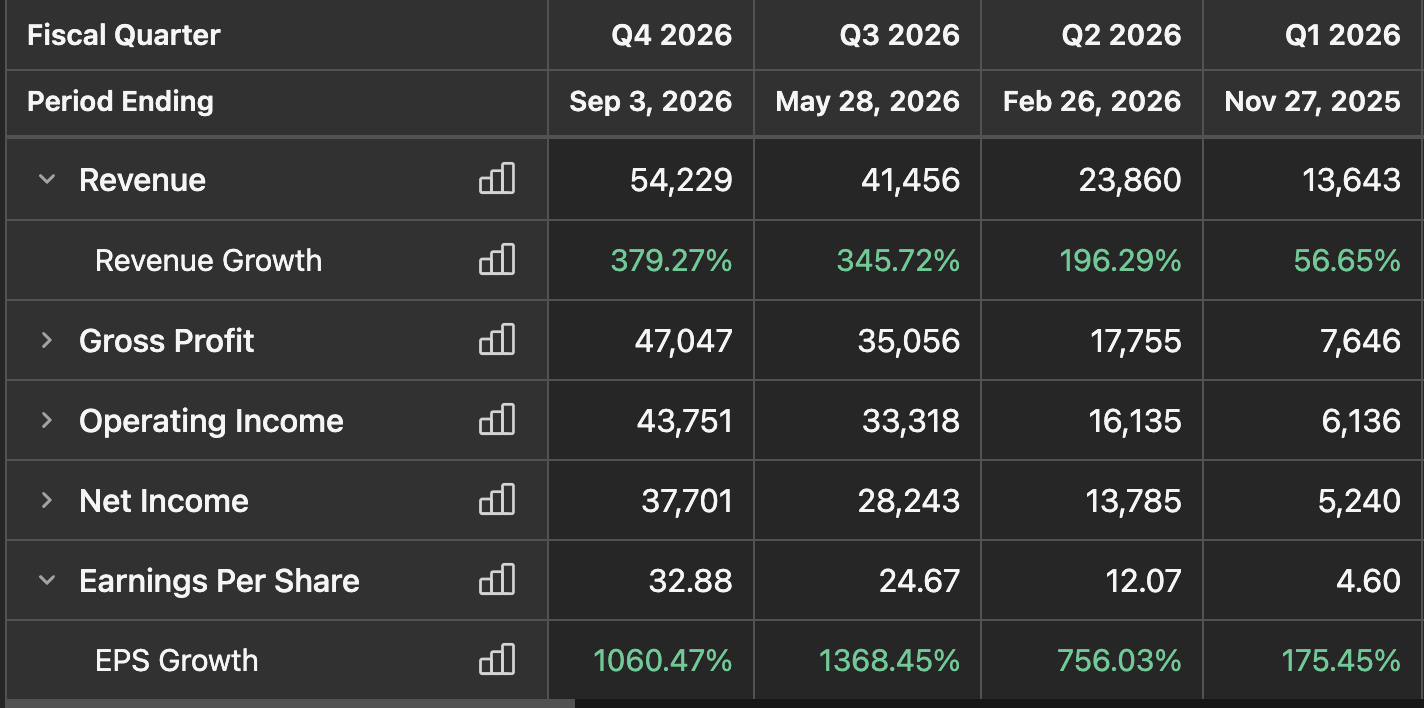
The stock is down however, as even these amazing numbers were not enough to move the needle for investors. More and more, it seems that the issue is going to comps that are impossible to beat QoQ even with the insane demand for memory right now in the AI narrative.
My thesis on all these memory names is that there will be margin compression as technology innovates to use less memory and compute. GOOG 0.00%↑ just announced their Argon model which does just that. The pressure on the chip and memory consumers, - i.e. the Googles, Metas, and other big tech of the world is too great. They have too much incentive to reduce their capex spend by advancing technology. To do more with less.
Back to MU 0.00%↑ earnings.
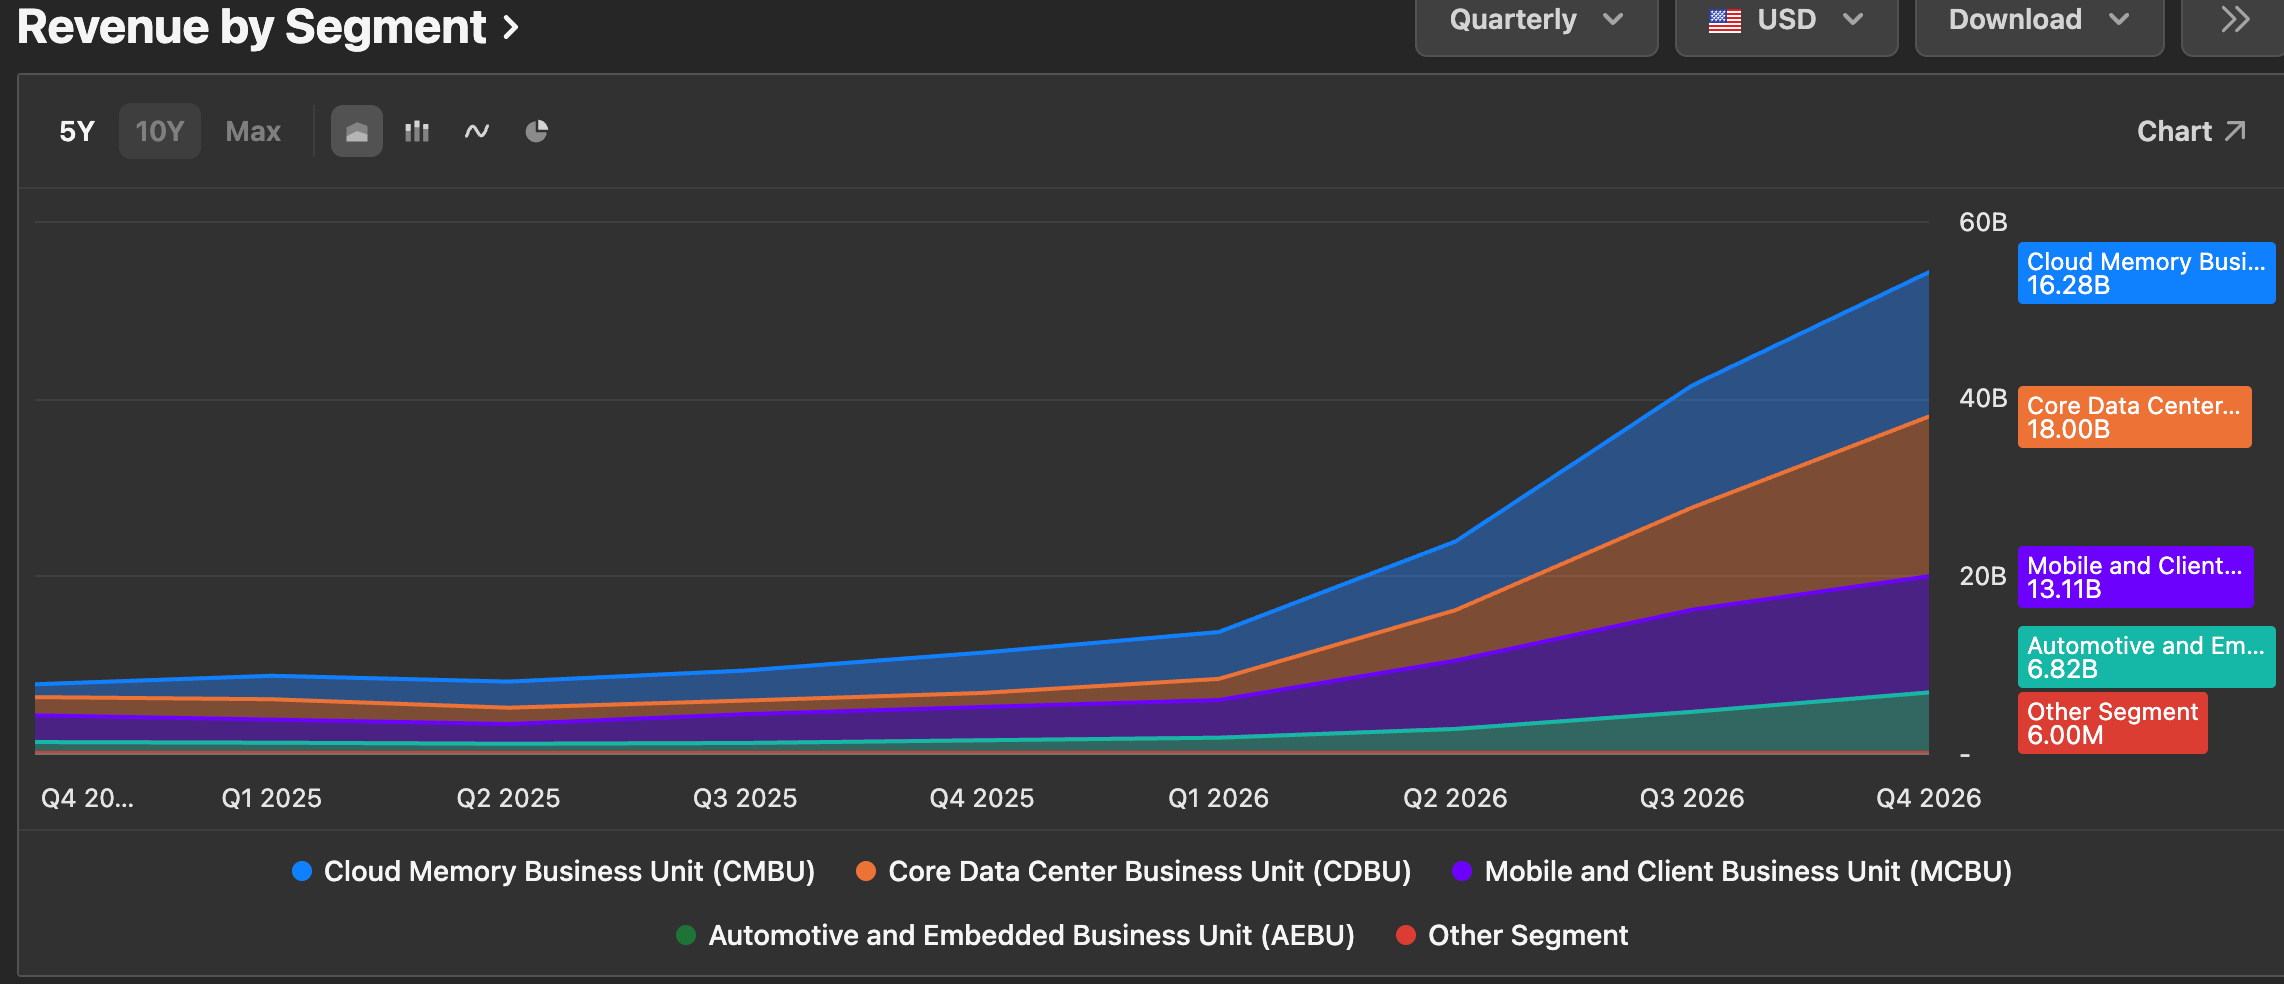
Their revenue segment chart shows that the core data center unit is the largest segment of their revenues which is followed closely by the cloud memory and mobile and client business units. All business units seem to be growing hand over foot besides the other segment which is not a meaningful contributor to revenues anyways.
Cash and debt look amazing as well with a $68.27B net cash position as of the latest quarter. Total debt sits at only $5.18B, so they are well capitalized. The cash flow from operations can definitely come to the balance sheet as their free cash flow is a healthy $32.86B with capex only at -$11.11B.
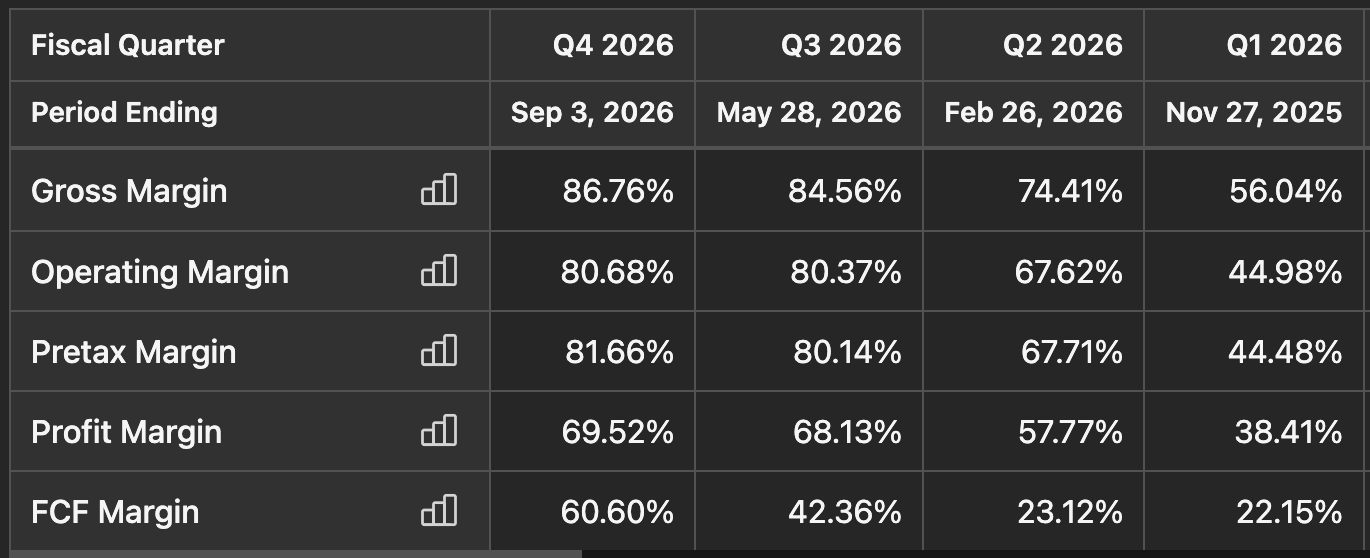
Finally, the margins of the business are exceptional with gross margin at 86.76%, operating margin at 80.68% and FCF margin at 60.60%. And this is the crux of the issue. These margins will not last forever. There will be margin compression at some point in the future. When that happens the stock will be hit massively.
I believe that is what the market is realizing today with the stock being down in my opinion. Feel free to share your thoughts below!
As always, my content is not financial advice, so please do your own due diligence when investing your money.
The beat matters less than whether the guide converts it into a durable revision cycle; semis can clear the quarter while the market is already underwriting the next capacity step. I’d watch forward pricing and capex discipline more than the headline EPS reaction.