

What a drop in GOOG 0.00%↑ stock today after it’s earnings. This drop has erased $400+ billion of market cap overnight. Let’s take a look at the earnings numbers.
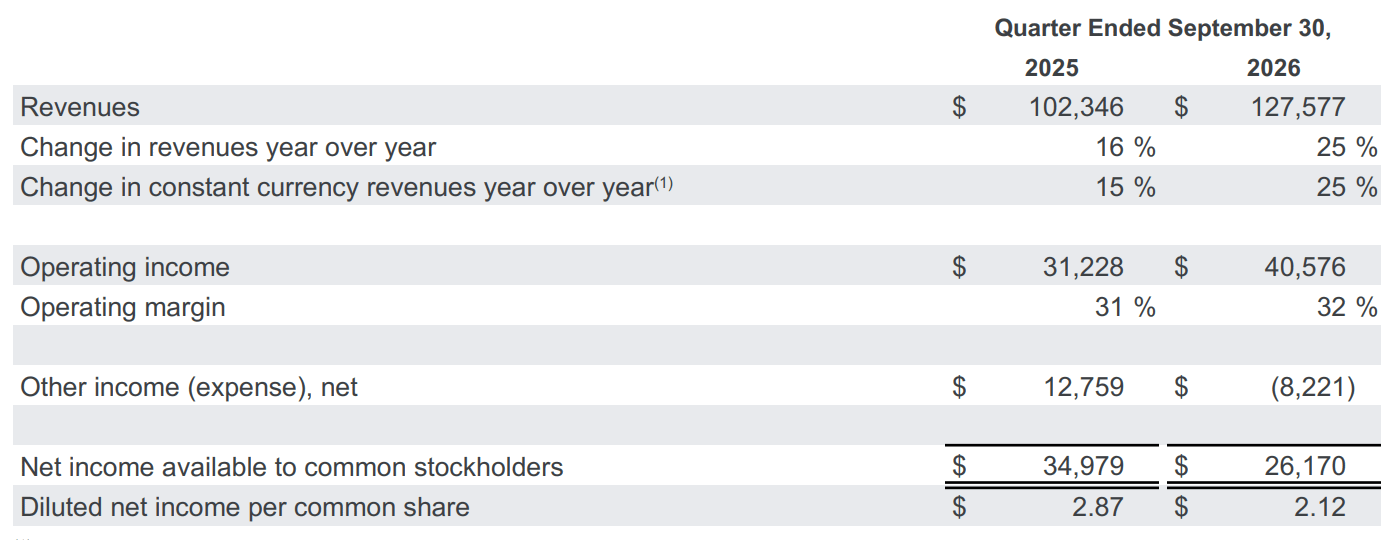
Revenues came in 25% higher YoY to $127.6 billion with operating income 32% YoY to $40.576 billion. There was a one-time hit of $8.221 billion from European charges that brought down their net income to $26.17 billion and their diluted EPS to $2.12.
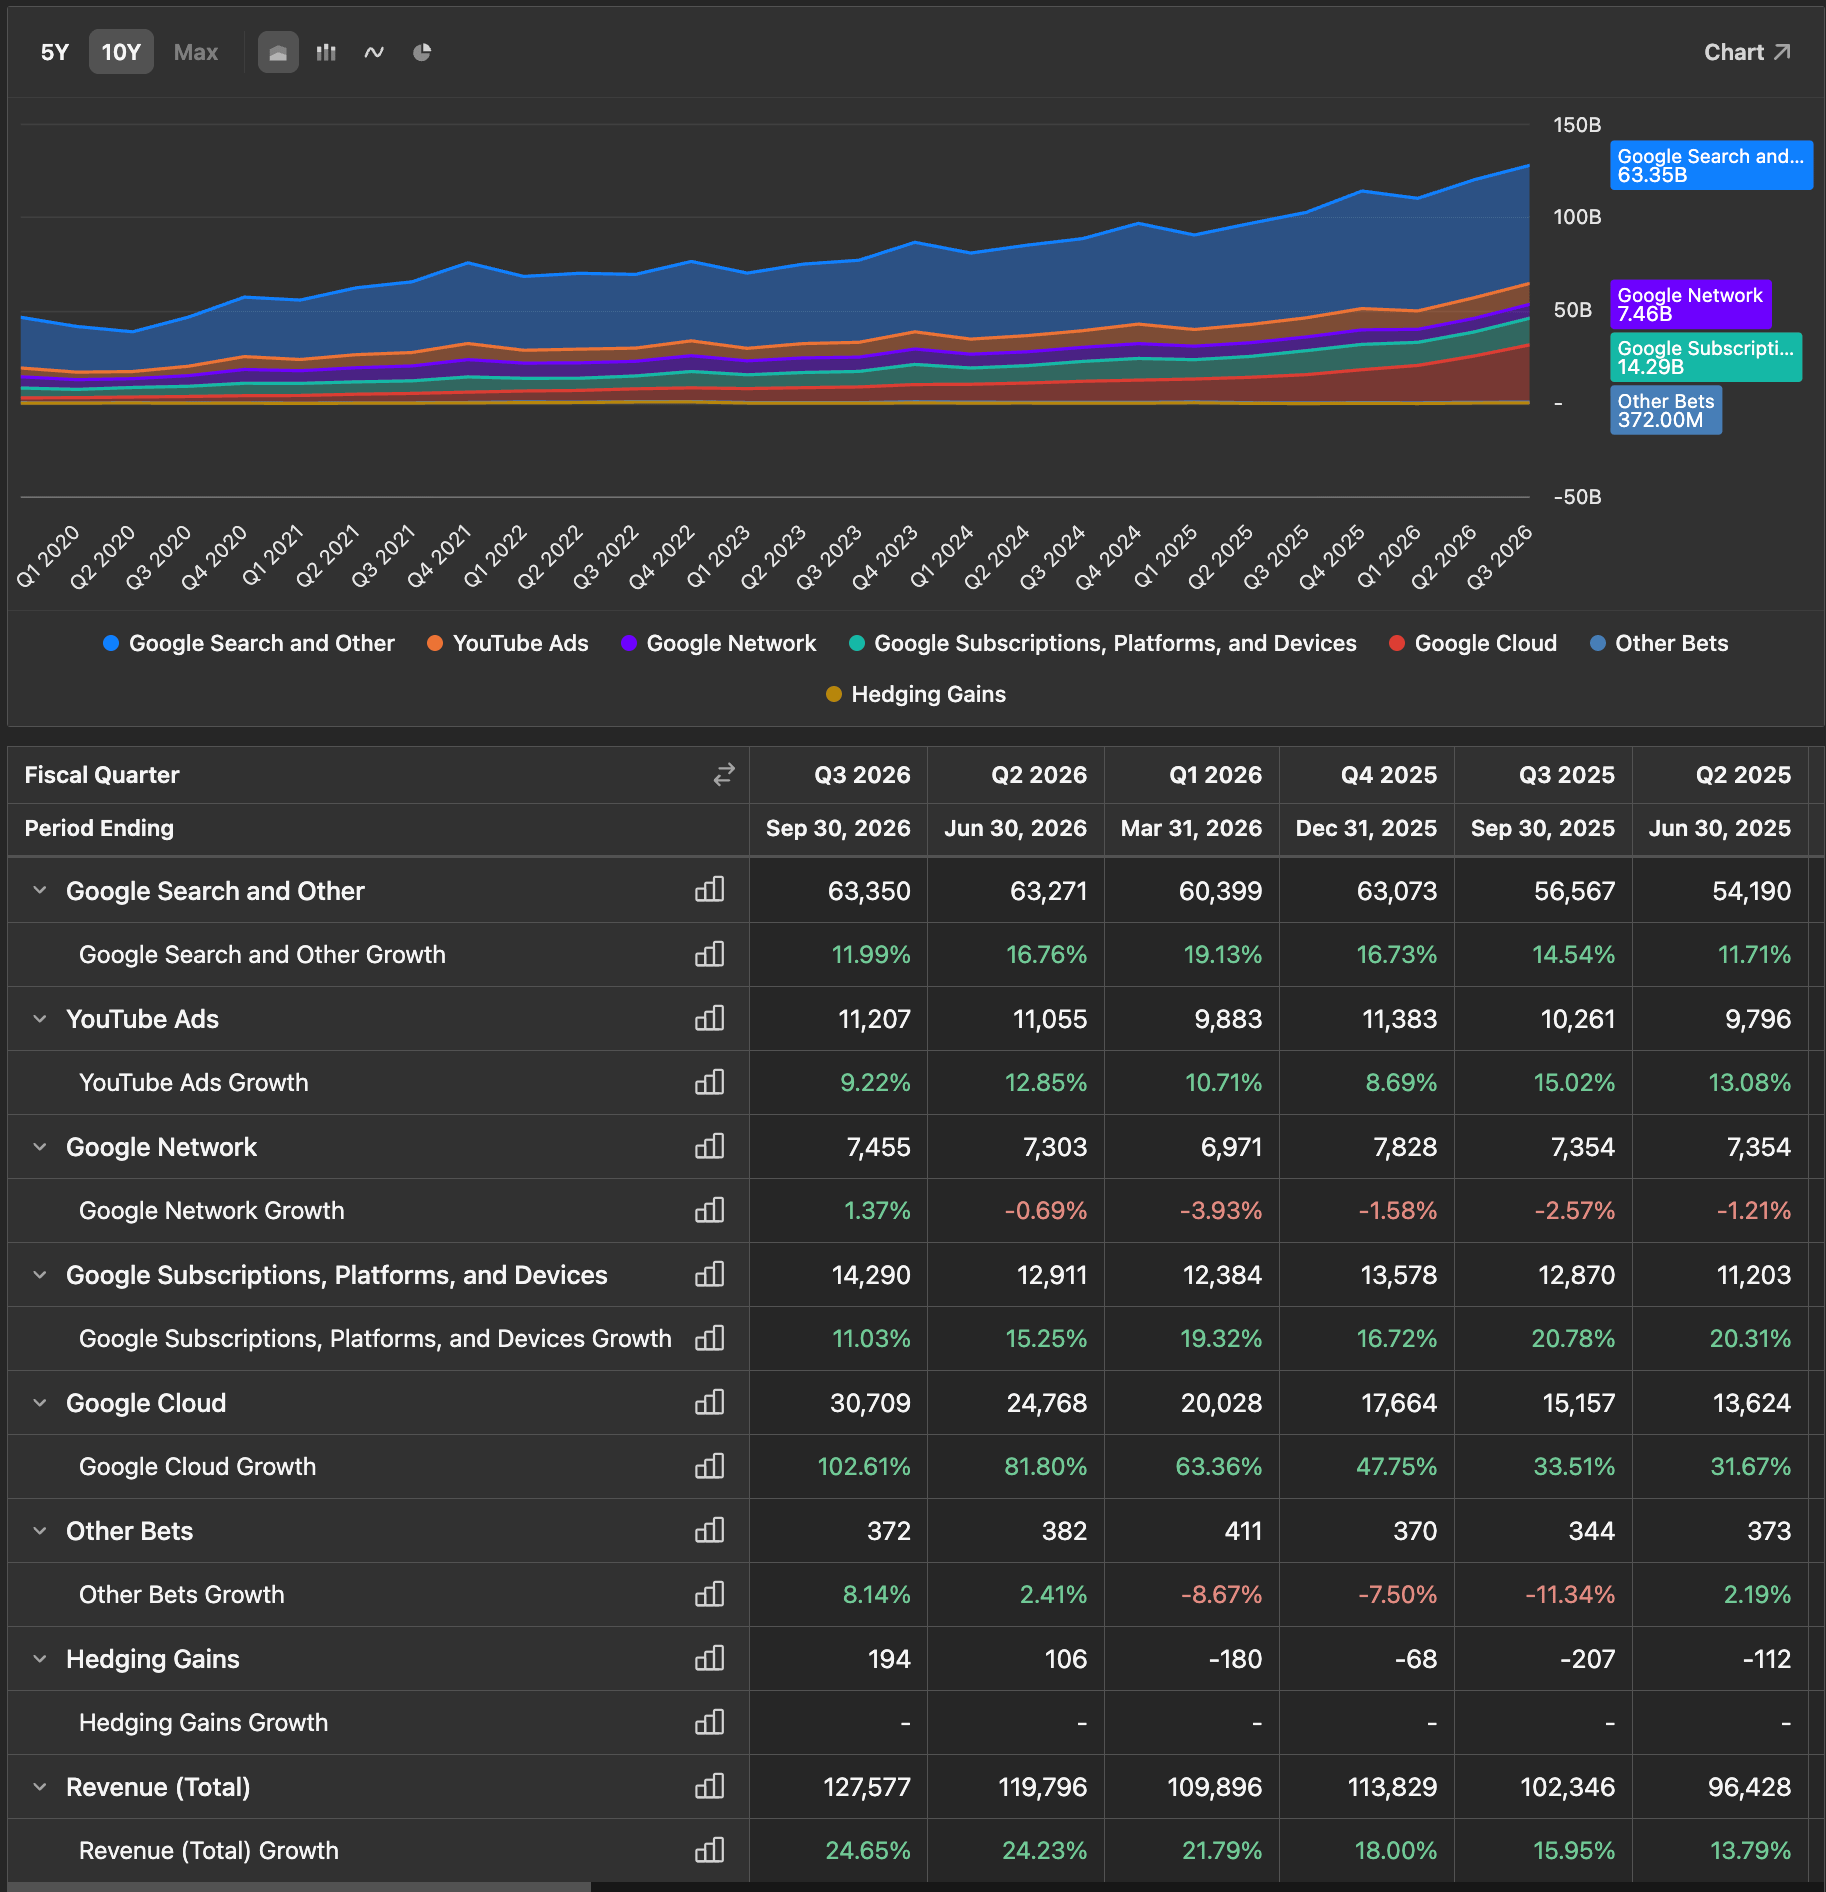
Looking at the segment revenue on stockanalysis.com, their Google Search and Other segment came in at 12% or $63.35 billion which was lower QoQ. They attributed this to foreign exchange effects but they also said that search query growth was the highest in 5 years. Even so the monetization in AI mode is less and they may have to address that pain point at some point soon.
Investors will also need to determine whether the drop in search is meaningful AI disruption or not. This was the same talk when AI first came out as well, so it looks like those worries were just under the surface for investors.
The real star of the show was their cloud coming in at 103% growth to $30.709 billion. The growing TPU sales segment will be a big driver of the cloud going forward. Plus this shows that they are getting market share from rivals Microsoft Azure and Amazon AWS.
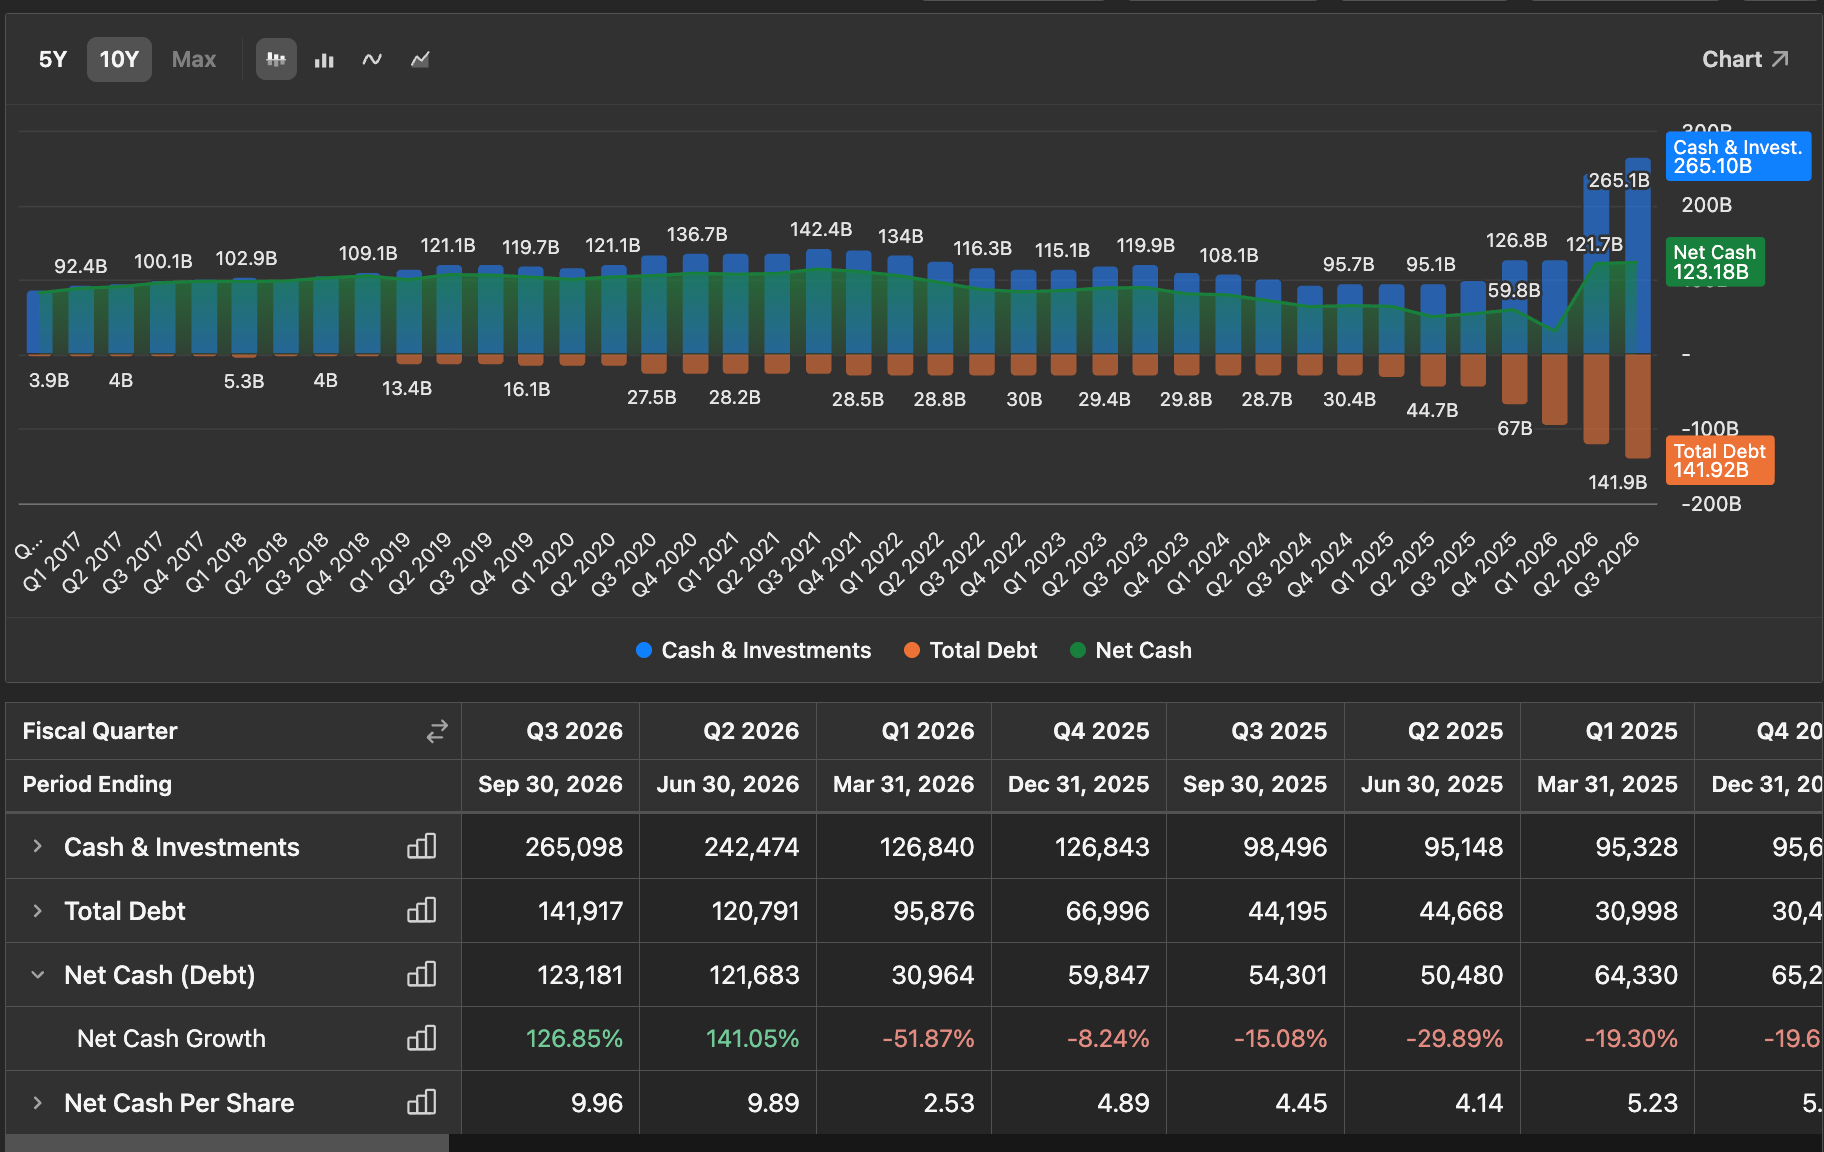
Net cash is still good at $123 billion but debts are increasing rapidly which is
another source of concern. As management states in their investor letter, they issued shares and unsecured notes to continue funding their AI ambitions.

Management has guided for significantly higher capex in 2027 compared to 2026 so there will be no mitigation in capex for now. However, their backlog in immense sitting at $561 billion for the next 2 years. GOOG 0.00%↑ expects to recognize more than 55% of the $561 billion backlog (roughly $310 billion) as revenue over the next 24 months.
So the demand is there for them to continue spending to get that ROIC, but investors are getting nervous as spend keeps creeping up. One thing I noted this morning on Substack is that capex is not going to be the same 1 year from now.
Buying power is getting eroded through inflation, so the CFOs of these mega cap tech companies might be realizing that they must take the pain now in order to realize a massive bonus when that same buying power won’t compound as much.
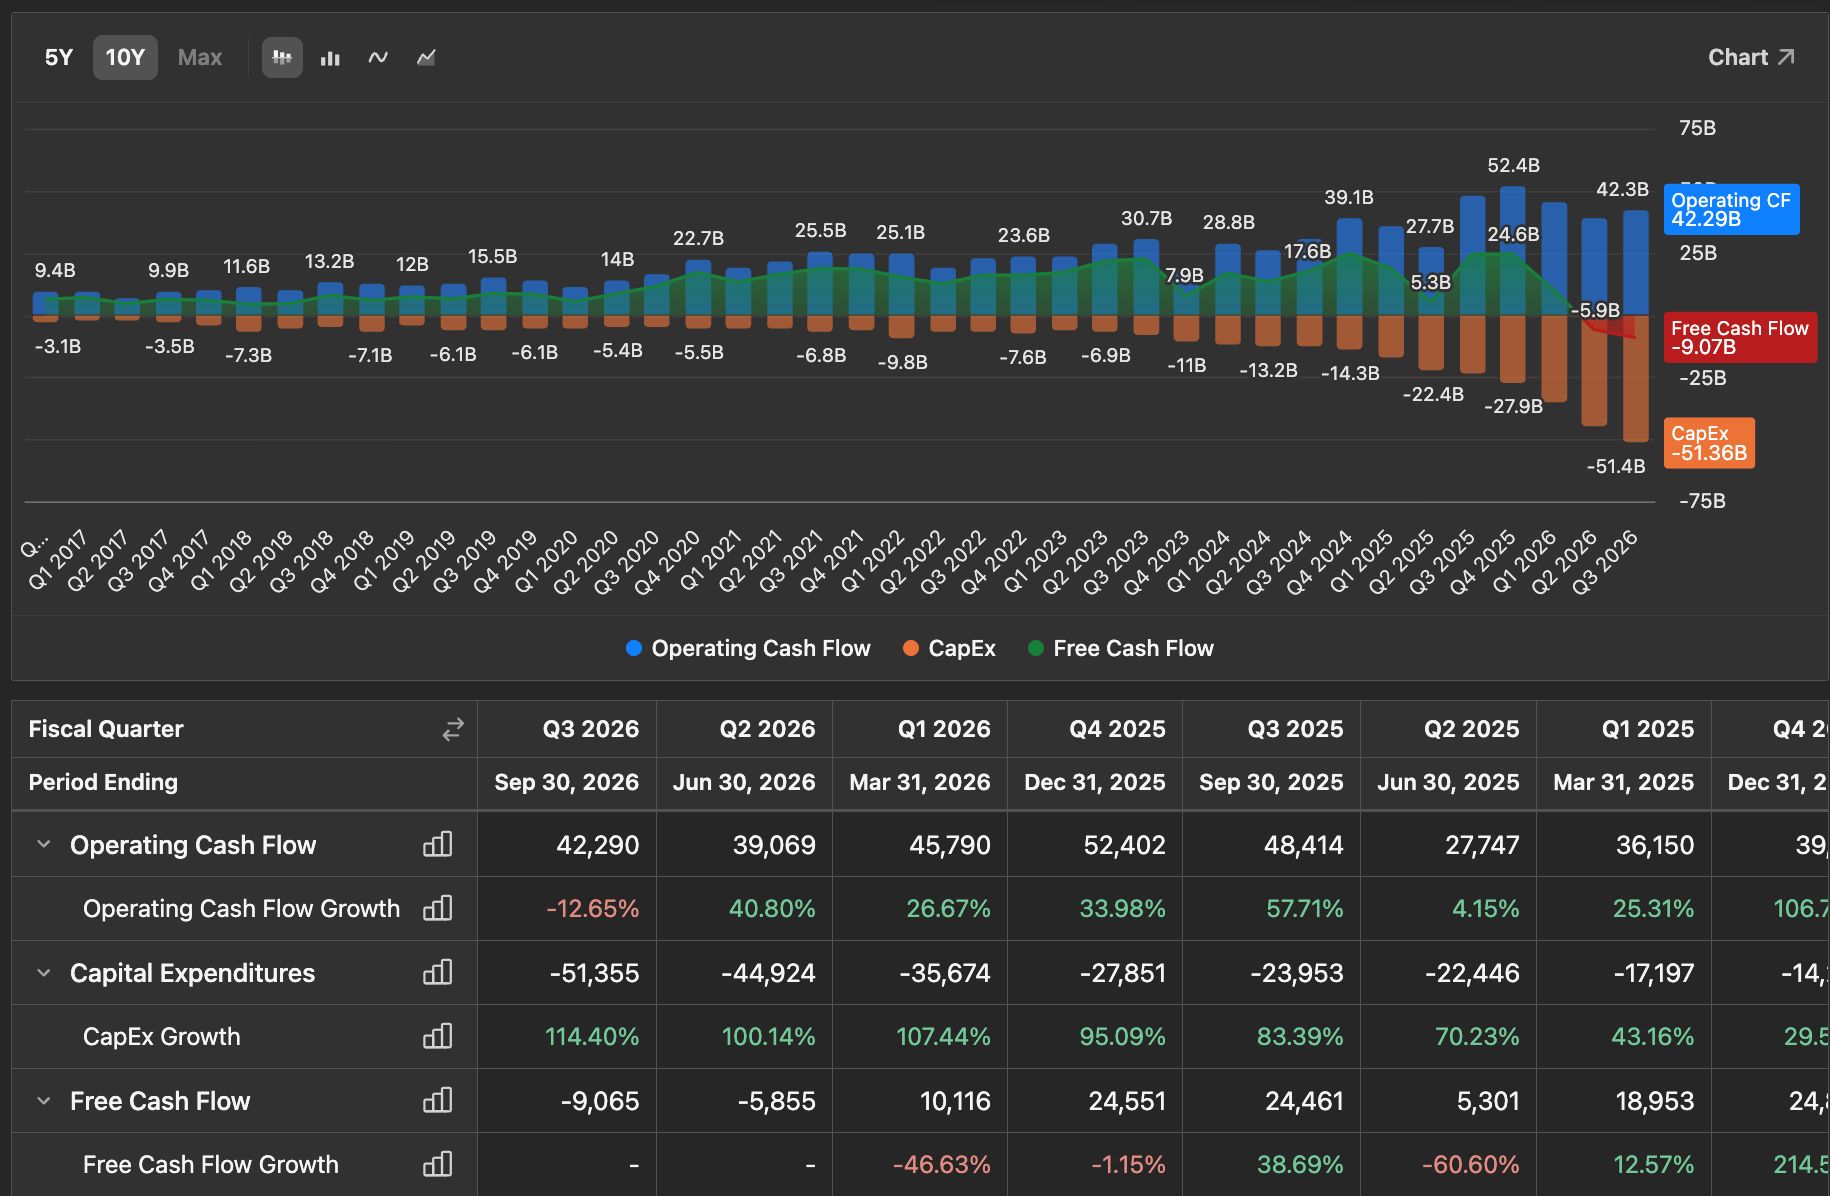
This does lead to declining free cash flow as seen above. They reported -$9.07 billion in FCF because of that one-time European charge which was much more than anticipated by investors and analysts.
However, their operating CF is increasing on an annual basis, so they are getting ROIC on their capex. The question is whether it is enough or greater than their spend.
As always, my content is not financial advice, so please do your own due diligence when it comes to investing your own money.