

Author Note: I have sold out of my position in META 0.00%↑ before the earnings call at around $720 per share. I sold because I did not like the trajectory of the capex spend and negative free cash flow growth at the company. The legal woes were also a factor in the decision. This does not prevent me from owning the shares in the future if I see things changing.
META 0.00%↑ is dropping like a rock thrown into a lake. The reason is the news coming out of their recent earnings report. Let’s take a look at the numbers in this quick look at META 0.00%↑.
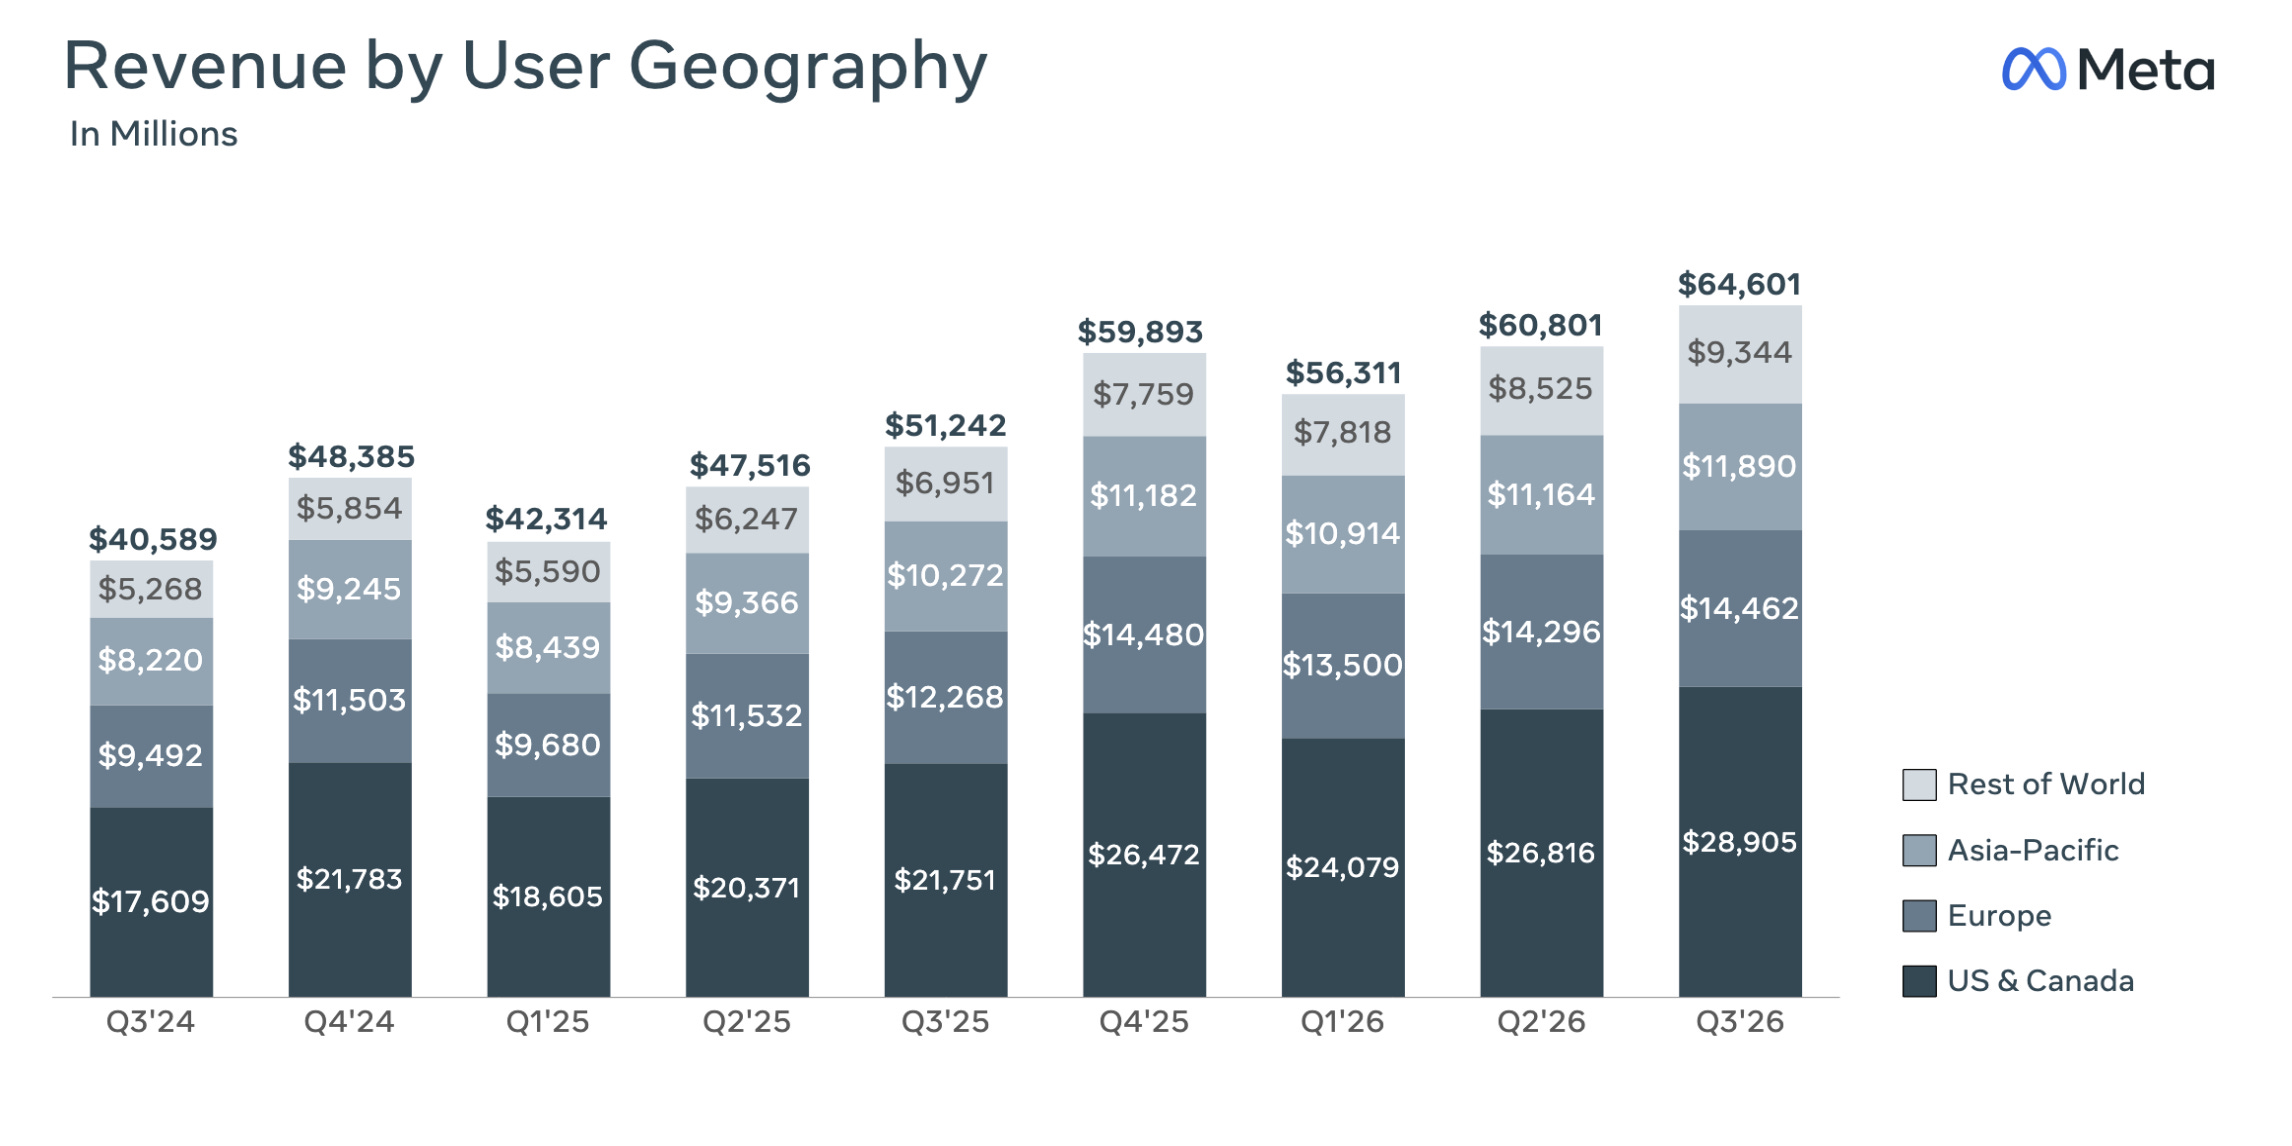
Revenues came in at $64.6 billion for Q3’26 and the breakdown is shown by geography below. Most of that money, approximately $63 billion of it, was generated from the advertising side of things.
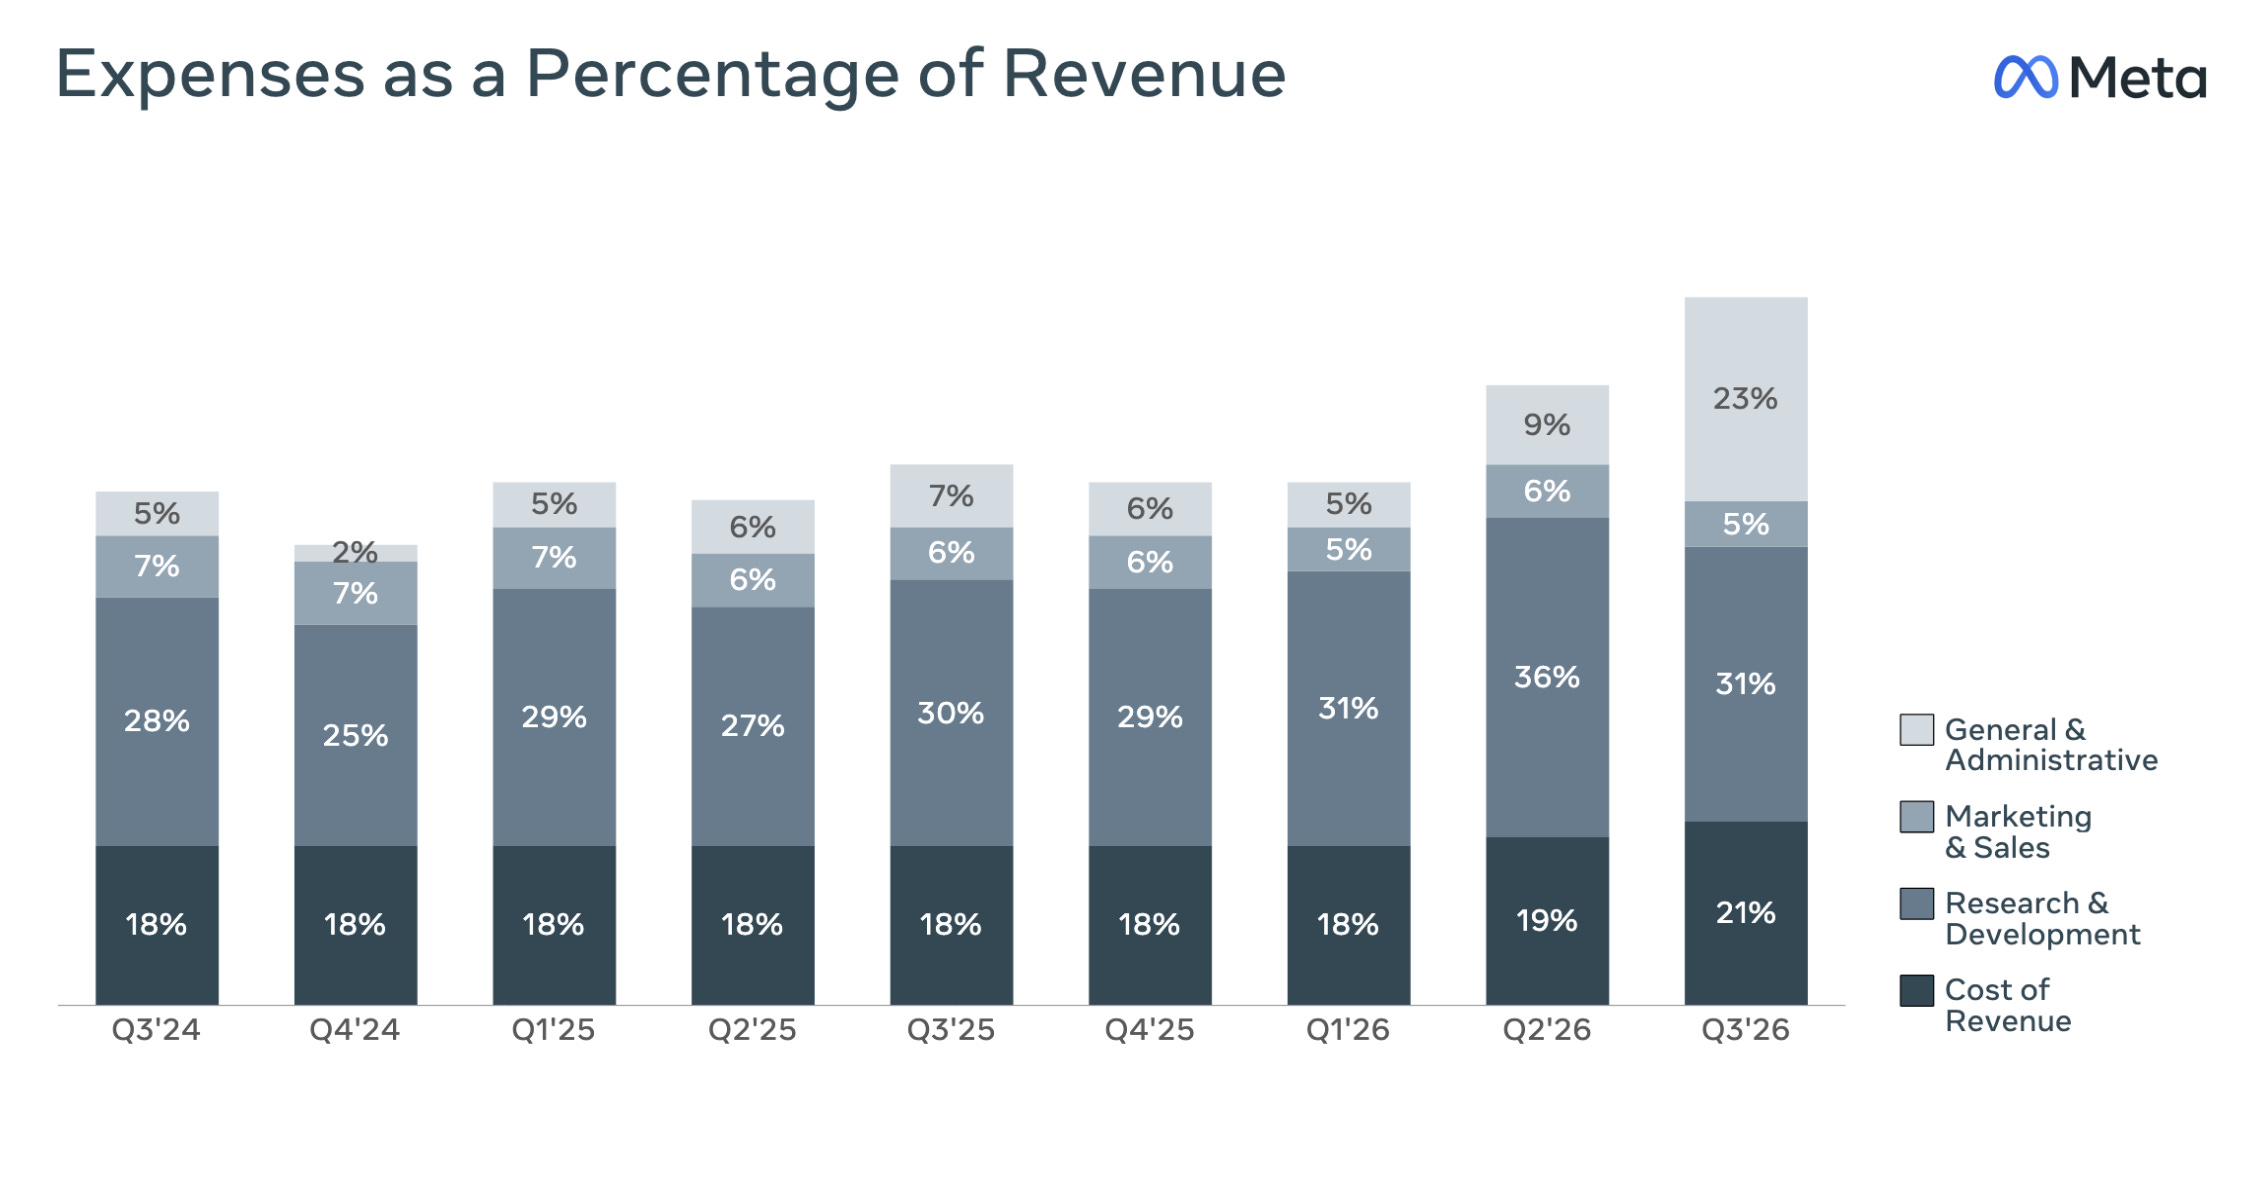
The expenses showed a huge percentage increase in the G&A costs but all the other segments seemed to be inline. Net income came in at $9.86 billion, diluted EPS at $3.83 and free cash flow at -$2.12 billion. Importantly, due to ongoing litigation settlements, their income from operations would have been $22.88 billion instead of the $12.99 billion and their diluted EPS would have been $7.40.
This shows the impact that the settlements are having on the bottomline at a time when META 0.00%↑ really can’t be spending on yet another expense. As a result free cash flow is now negative which is insane for a company that used to be so asset-light and a cash cow.
In addition, they raised the low end of their AI spend for 2026 from $130-$145 billion to $135-$145 billion which is inline with the continual raising of capital expenditures by all AI tech names.
Probably one of the most concerning things coming out of the earnings call is the establishment of a new class C of shares similar to how GOOG 0.00%↑ is structured. These are non-voting shares that do not affect Mark Zuckerberg’s voting shares.
According to their own investor letter:
Creating a New Class of Shares for Capital Raising, Employee Compensation, Potential Acquisitions, and Other General Corporate Purposes – The scale of investment required to compete, sustain growth, expand infrastructure, and pursue new strategic initiatives amidst the AI transformation taking place in the industry is significant. The Special Committee determined this new class of common stock will provide Meta the ability to finance its growth and help the company remain a leader among fierce competition both domestic and international.
So this is more dilution for shareholders just by a different name. Instead of taking on direct debt, they will be issuing shares to fund more AI spending.
This, plus the weakness in AI names, is probably why META 0.00%↑ is tanking as of the time of this writing. Like I mentioned in my note, I sold out of META 0.00%↑ before this earnings call, but I would revisit this name if it fell much more.
As always, my content is not financial advice and you should do your own due diligence when investing your own money.