

It has been a whirlwind of economic activity, earnings and news events these past few weeks. I thought it might be good to do a recap article for my subscribers to understand my positions, timelines and the thesis behind these stocks.
Before we start, here is the portfolio as it stands at the time of this writing.
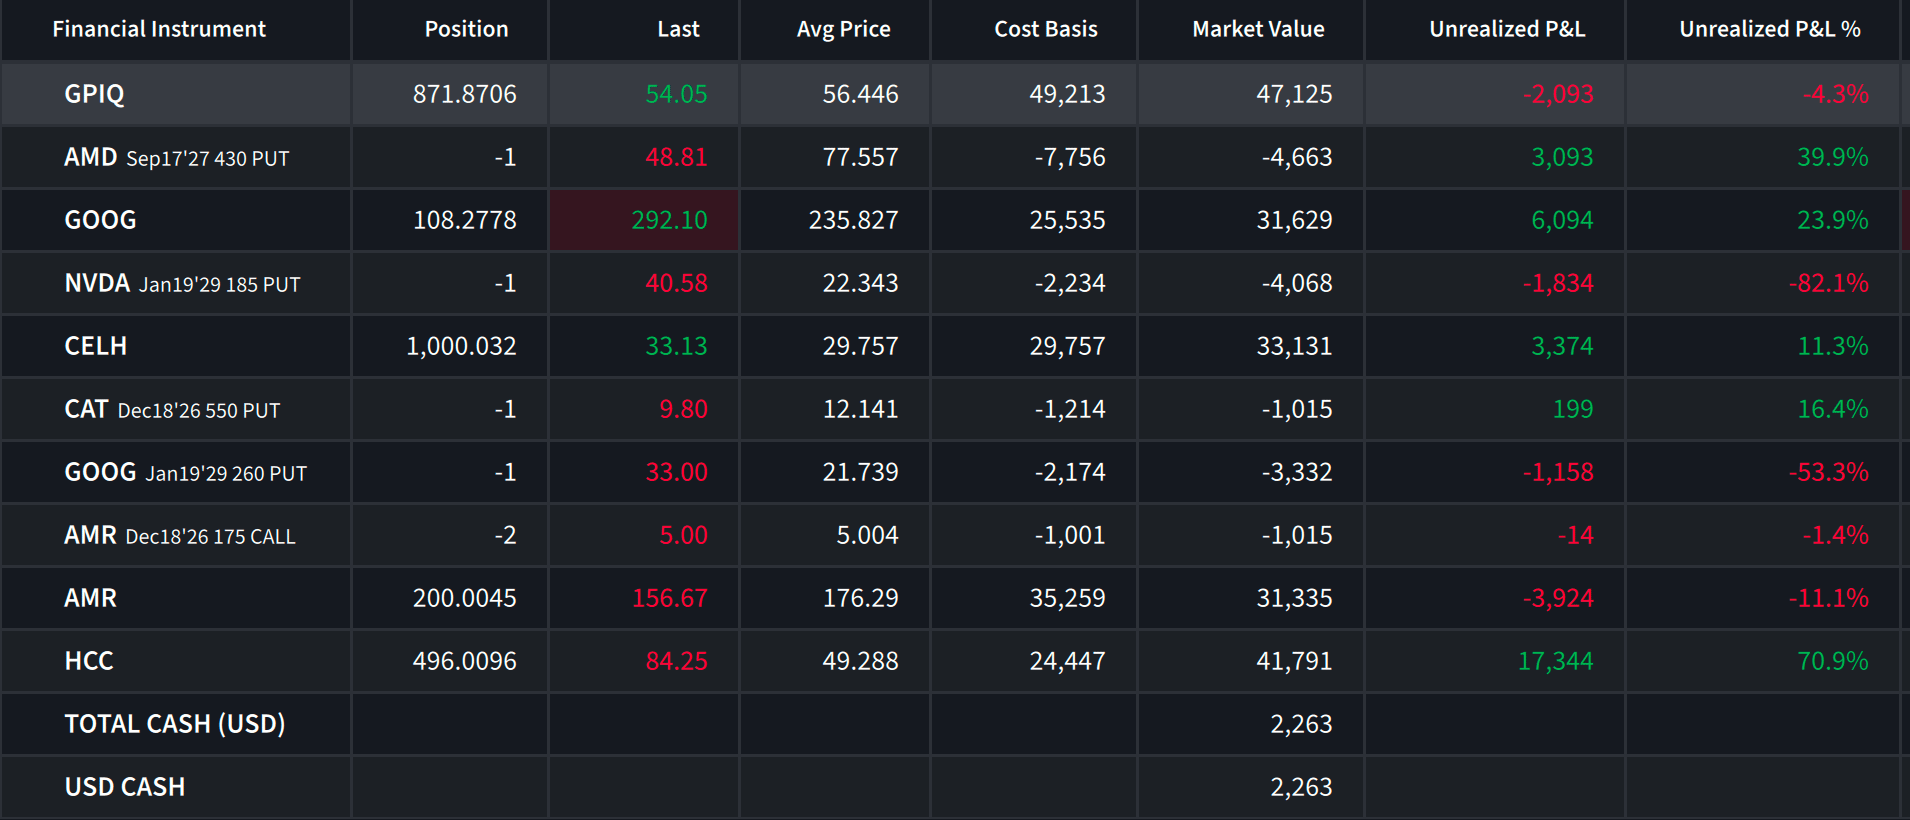
Let me discuss these positions in terms of their overall sector and industry to save you the monotony of reading through listed equities for debate. As always, all my stock analysis data and research is done using StockAnalysis.com, so if you want to check financial metrics and ratios for positions you own or want to own, click here to go to StockAnalysis.com
Industrials & Mining
My two met coal plays continue to be HCC 0.00%↑ and AMR 0.00%↑. Some things have become clear to me in hindsight looking at these two companies.
HCC 0.00%↑ continues to be a bright spot in my non-AI investments. I was fortunate enough to buy HCC 0.00%↑ when it was trading in the $40’s so I have had a unrealized profit of anywhere from ~60% to over 100%.
Warrior is really the better met coal play. Their long-wall mining approach coupled with their barge and freight access have pushed them to the lowest quartile on the cost curve which is an enviable position when looking at margins across the met coal space. Due to this, they were able to post nice free cash flows in the latest quarter and issue a special dividend to boot.
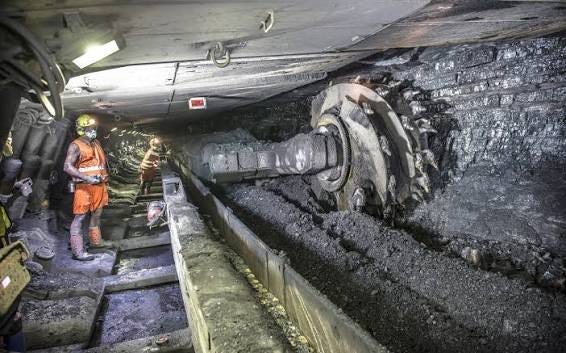
What has become even clearer to me is that AMR 0.00%↑ is quite the opposite. Even before the DTA damage which affected their loading and shipping of met coal to their customers, their cost curve position was not great. Margins were thin and the damage was just the straw that broke the camel’s back if you will. Now that the DTA machinery needs to be replaced outright, a lengthy news update is now a lengthy fix well into 2027.
However, I did not miss the rally completely. I did run options on the AMR 0.00%↑ shares using covered calls a few months earlier and I have a few new options that I ran today in fact. These options expire in Dec if everything holds pat. If they get challenged, I will be rolling up and out to continue benefitting from any cyclical upside swings in met coal.
I added to my AMR 0.00%↑ position after it fell back to earth following supply-side disruptions which elevated the prices of all met coal stocks. I’m now sitting on 200 shares that, for all intents and purposes, are stuck in the mud. Suffice it to say,
if shares rally due to another supply-side crunch (not demand-side), I will be letting go of these 200 shares to add to HCC 0.00%↑ and possibly other names.
A new addition to my portfolio you may notice is the sold put on CAT 0.00%↑. I haven’t discussed CAT 0.00%↑ in a deep-dive or quick dive before, but it is coming. Their recent price drop plus the fundamentals they are sporting, have caught my attention for at least a quick turnaround play in the options market. Ideally these shares stay above the $550 strike price put I have, but if assigned, I deem good premium on the covered calls I would sell in that scenario.
Technology
I sold a long-standing position in META 0.00%↑ recently for various reasons. The amount of debt that some of these hyperscalers are getting into gets doubly worse with the removal of their traditional asset light business models. META 0.00%↑ is committing to higher and higher debt and share issuance to fund the buildout, but has one of the most singular revenue streams of all big tech.
That stream is based almost exclusively on advertising revenue, which we know, is not the most steady revenue stream. In times of tight advertising budgets, companies are known to pull advertising dollars and this can destroy META’s revenue. On ther other hand they are trying to diversify and show revenue from other sources like agentic AI through their Muse models which is an encouraging sign.
However, I would much rather put that money into GOOG 0.00%↑ which has had a diversified business even before the advent of AI with YouTube, GCP, Waymo, AI investments, Search and more. The hooplah about their search getting decimated is far overblown in my opinion. They will be transitioning their traditional search into AI and agentic search over due time and will figure out how to monetize this new type of search to their benefit. For that reason, I added some shares to my existing base of shares on this recent drop after their earnings.
Moving onto my AMD 0.00%↑ and NVDA 0.00%↑ options. I haven’t done anything with my NVDA 0.00%↑ options after the scandal broke with Jensen and his affair. In my opinion, there is nothing to do. NVDA 0.00%↑ earnings will look tremendous and my put is expiring 2 years out. Let great companies compound your money and continue holding for maximum gain.
For my AMD 0.00%↑ put, there has been much action. I rolled the put out and down when I saw that huge drop of $70-$80 dollars in a day in the past two weeks. Unfortunately, that was not necessary, as this was a temporary blip and quickly reversed. Due to those rolls to avoid assignment, I have a $430 strike put that expires in September of 2027. The position is working with me and I have a significant 30 or 40% gain on the position once more. I will roll this put up to a closer expiration (and for a gain) once I get past 50% profit on the position.
Lastly, I have to briefly discuss my GPIQ 0.00%↑ ETF under this sub-headline because it is a Nasdaq-based ETF. I said this on my notes, but if GOOG 0.00%↑ were to advance materially closer to it’s intrinsic value closer to $400-$500, I would sell and add at least part of that money to GPIQ 0.00%↑. This continues growing my income-producing side of my portfolio which will fund more growth opportunities once it gets large enough. My readers know that I pursue growth AND income to create a synergistic flywheel to take advantage of all market conditions.
Consumer Discretionary
Finally, we round things out with consumer discretionary and that, of course, is my CELH 0.00%↑ position. CELH 0.00%↑ has been bouncing around the high $20’s to low $30’s for a while and I think it will stay that way until they can show growth in the core Celsius brand.
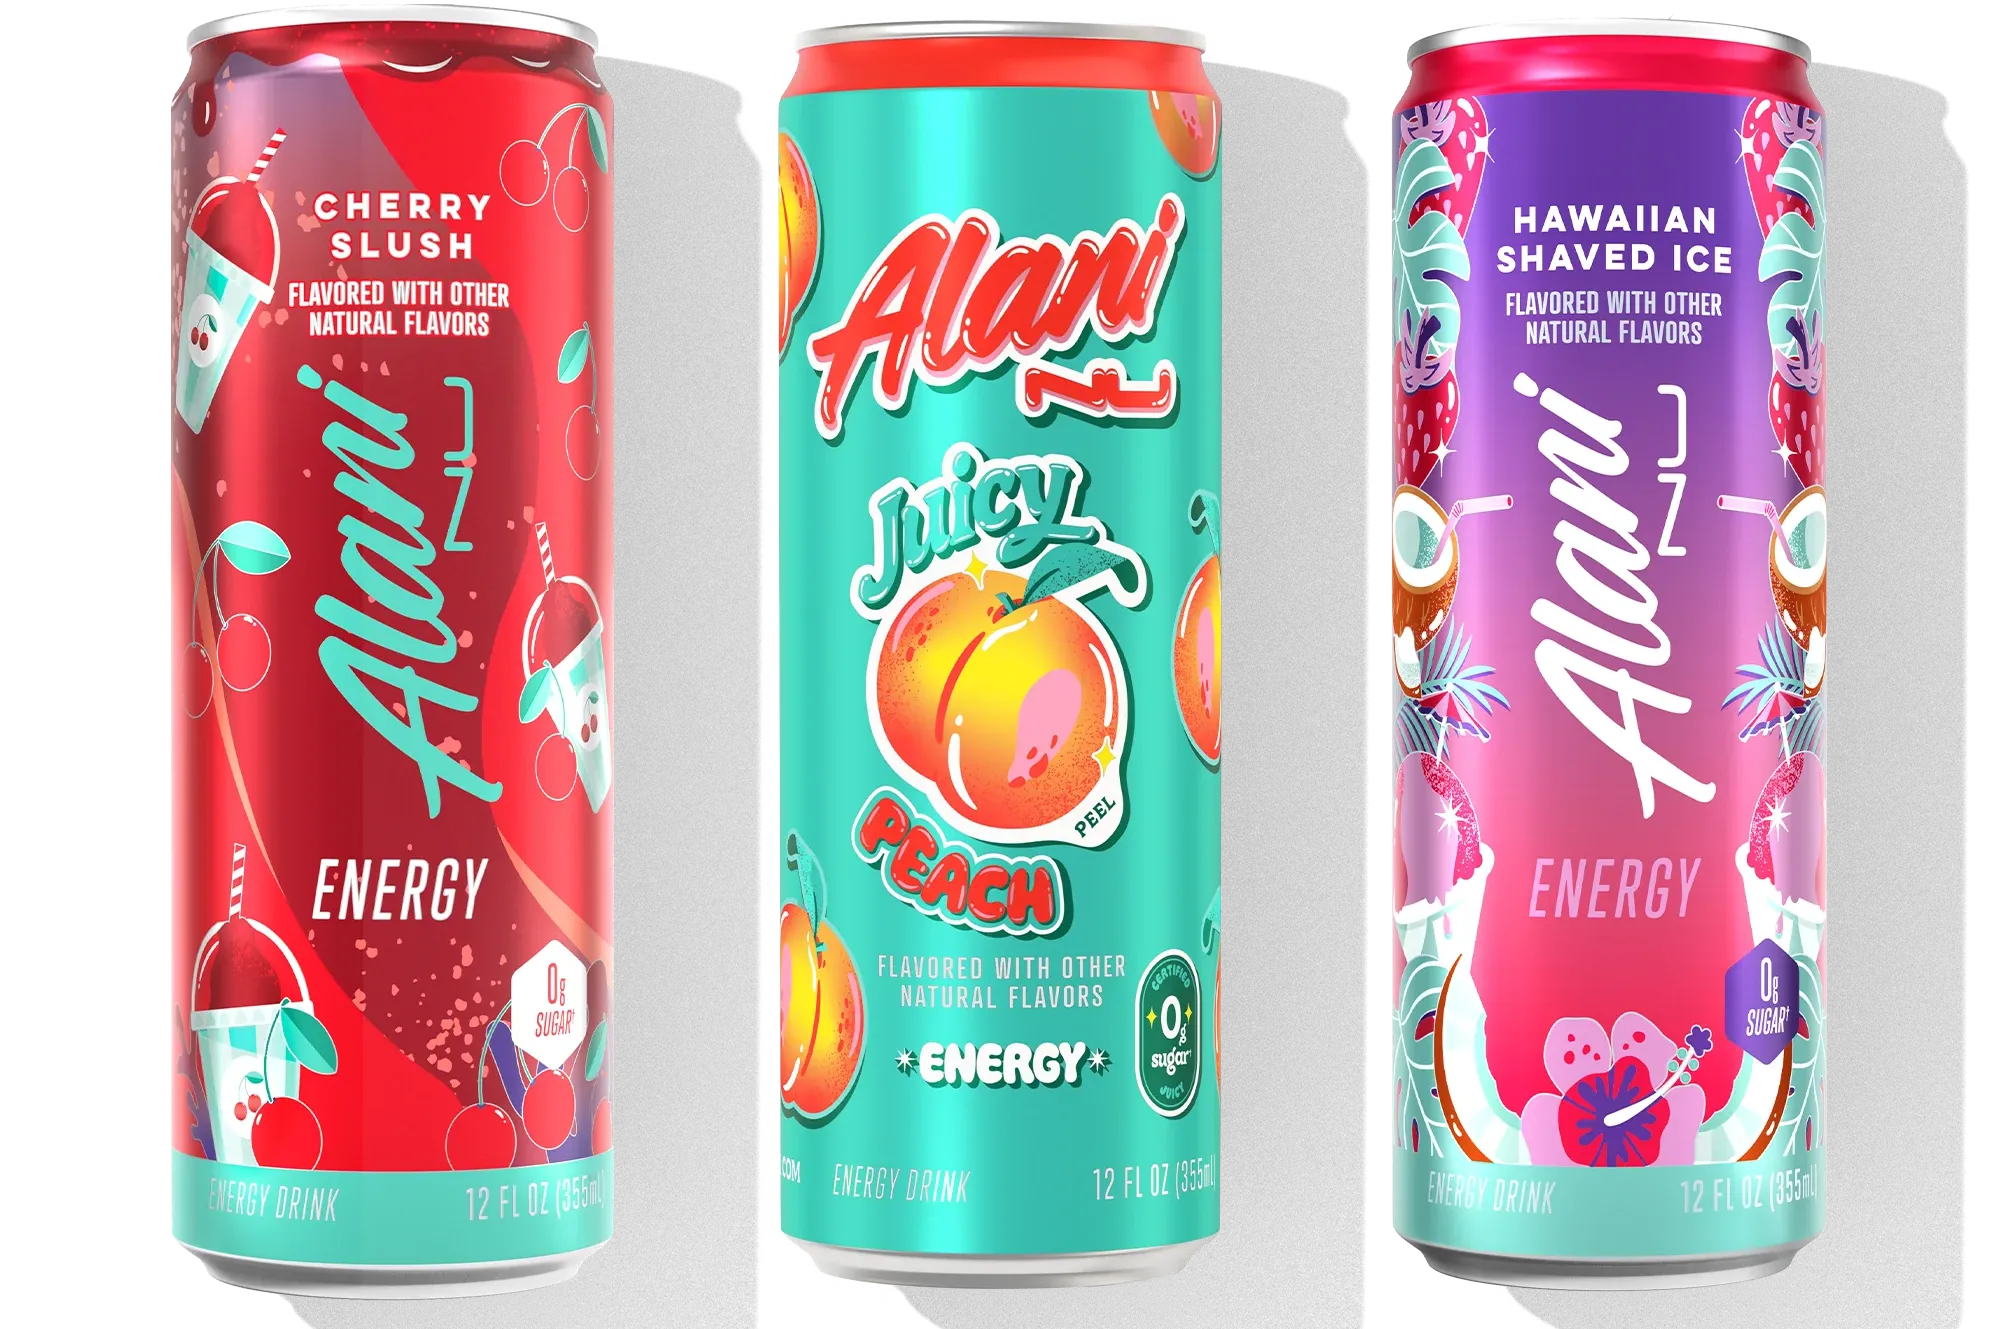
Their Alani Nu brand is ripping higher with growth and progress, so once they do their SKU optimization and really get Celsius growing again, they will be a powerhouse in the drink space.
I think CELH 0.00%↑ can rip higher into the $40’s easily, so this prevents me from writing any covered calls on my CELH 0.00%↑ shares. I will be watching CELH 0.00%↑ like a hawk to see if they can get the core brand growing again. I like what I saw coming out of the last earnings with the 3 presidents leading the charge for each brand. Let’s see if it leads to a nice return for shareholders.
As always, my content is not financial advice so please do your own due diligence when investing your own money.
Man look at that performance difference between $HCC and $AMR. I wish I wouldn’t seen the superiority of $HCC years ago. I didn’t realize being diversified and building another mine would be so beneficial.